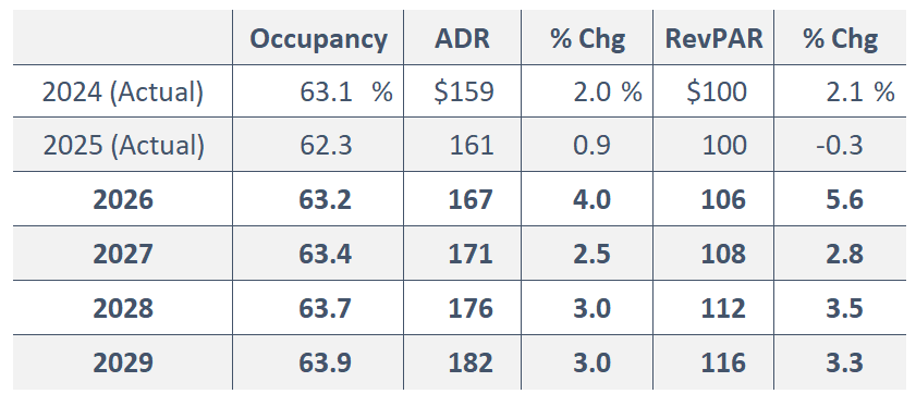
ADR, on the other hand, remains well above the pre-pandemic level, and rate growth in the fall months surpassed the gains from earlier this year during the FIFA World Cup. We expect ADR growth to wane in November and December given the typical travel patterns during the holidays and colder months. A slight moderation in RevPAR growth is on tap for next year in the absence of both the World Cup lift benefiting the industry and the robust 2026 vs. 2025 comparisons we are benefiting from this year. Nonetheless, we expect to end 2027 with modest occupancy and ADR increases.
Our latest U.S. forecast is as follows.
Without oil and trade flowing normally through the Middle East, and without an open-arms stance toward our biggest trading partners, inflation is heading in the wrong direction. Keeping hotel operating costs in line remains a challenge for the management companies and managers I speak to, and finding staff in a time of heightened ICE activity is another concern. More and more managers are turning to staffing companies to fill positions that are lacking applicants. Contracting out entire departments is also becoming more the norm than the exception. So many full-service hotels now do not fully “own” their valet, housekeeping, and banquet departments. I have a feeling this is just the beginning of a trend and we’ll see more of this staffing structure through the rest of the decade.
HVS offers the HVS MarketCast if you require an occupancy and ADR forecast for a specific market or submarket. Please reach out to me to learn more.
We also just completed our HVS Hotel Broker Survey Fall 2026. The general sentiment is that cap rates are set to increase, with the unavoidable culprit being higher interest rates. But perhaps the strong rise in RevPAR and generally “OK” outlook for 2027 will balance out the rising cap rates and allow the hotel value story to remain positive. That’s certainly what we are expecting, with some hotels faring better or worse than others.
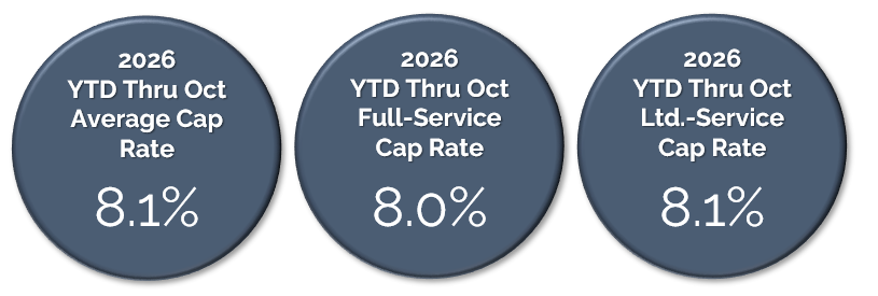
Source: MSCI Real Capital Analytics (Closed U.S. hotel transactions)
Despite the headlines and recent Fed interest rate hike, we remain busier than ever at HVS. Buyers and sellers are increasingly realistic about completing deals and understanding that these financing and deal-making realities are likely to be in place for a while. Moreover, coming off a solid fall season of RevPAR growth, T12 operating statements are looking healthy and are sparking significant activity on the refinancing front. We will keep monitoring how the fall travel season ends, and we look forward to another strong year in 2027.
About HVS Leadership
At HVS Americas, our thought leadership is guided by the HVS Standards & Excellence Committee, which includes the following industry leaders:
- Rod Clough, MAI, CRE, MRICS, President of HVS Americas
- Anne R. Lloyd-Jones, MAI, CRE, Director of Consulting & Valuation Services, National Practice Leader
- Katy Black, MAI, Managing Director, Leader of the Mountain West Region and the HVS Americas Complex Consulting Group
- Tanya Pierson, MAI, ISHC, Senior Managing Director, HVS Minneapolis
- John Lancet, MAI, Senior Managing Director, Practice Leader of Southeast and Caribbean Regions
- Carrie Russell, AACI, MAI, RIBC, ISHC, Senior Managing Partner of HVS Canada
- Chelsey Leffet, Chief Operating Officer, U.S. Consulting & Valuation Division
- John Berean, Managing Director, HVS San Francisco and HVS Honolulu
- Ryan Mark, Senior Vice President, HVS Denver
- Marc Greeley, Senor Director, HVS Chicago
Behind HVS Americas is a 35-member senior leadership team of seasoned hospitality consultants with deep expertise across the industry. With professionals based in more than 40 cities from Buenos Aires to Montreal, we bring both local market knowledge and a comprehensive view of the Americas. As the year progresses, we are closely monitoring hotel trends and committed to helping our clients make informed, confident decisions.