Market Report

2026 HVS Lodging Tax Report - USA

October 26, 2026
This 16th annual Lodging Tax Study presents data on city, state, and special district lodging and sales taxes imposed on lodging sales. We provide historical data on tax rates and collection and distribution of revenue from lodging taxes levied in all 50 States and the 150 largest US cities. Our analysis of 25 major U.S. hotel markets shows more markets declining than growing in 2025. Through August 2026, RevPAR rose in all but one market, signaling broad-based improvement in hotel performance.

Source: iStock.com/Evgeny Kuklev

Lodging Industry Overview

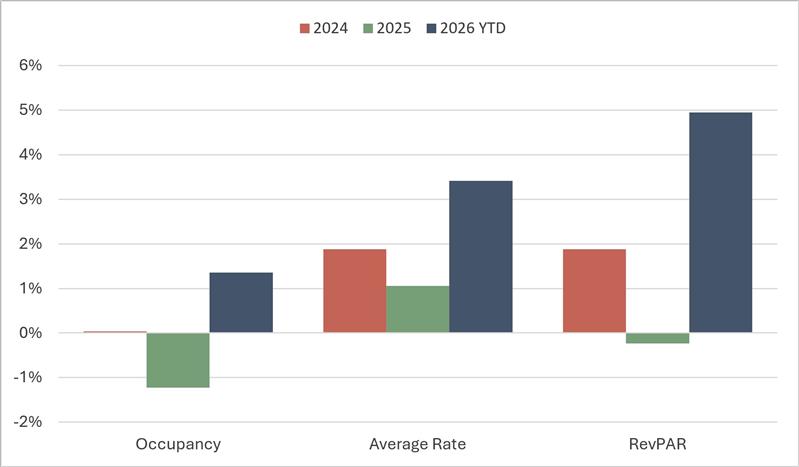
Since room sales generate lodging tax revenues, an overview of hotel market trends provides insight into the industry’s current and future fiscal impacts. As documented in our 2025 HVS Lodging Tax Study, the national lodging market has experienced recent growth in average daily room rates and revenue per available room. However, occupancy levels have remained relatively flat. The Average Daily Room Rate (“ADR”) represents the average revenue earned for each room rented in a hotel. Revenue per available room (“RevPAR”), the product of ADR and occupancy rate, is a standard industry metric that combines the effects of occupancy and room rates on overall revenue performance. ADR and RevPAR increased in 2024, while RevPAR declined slightly in 2025 as occupancy fell. Through the first eight months of 2026, all three metrics have improved compared to the same period in 2025. The figure below compares year-over-year growth in occupancy, ADR, and RevPAR for the entire U.S. lodging market, based on CoStar data, from 2024 through August 2026.

Year-Over-Year Changes in U.S. Lodging Market Figures From 2024-2026
Source: CoStar
 
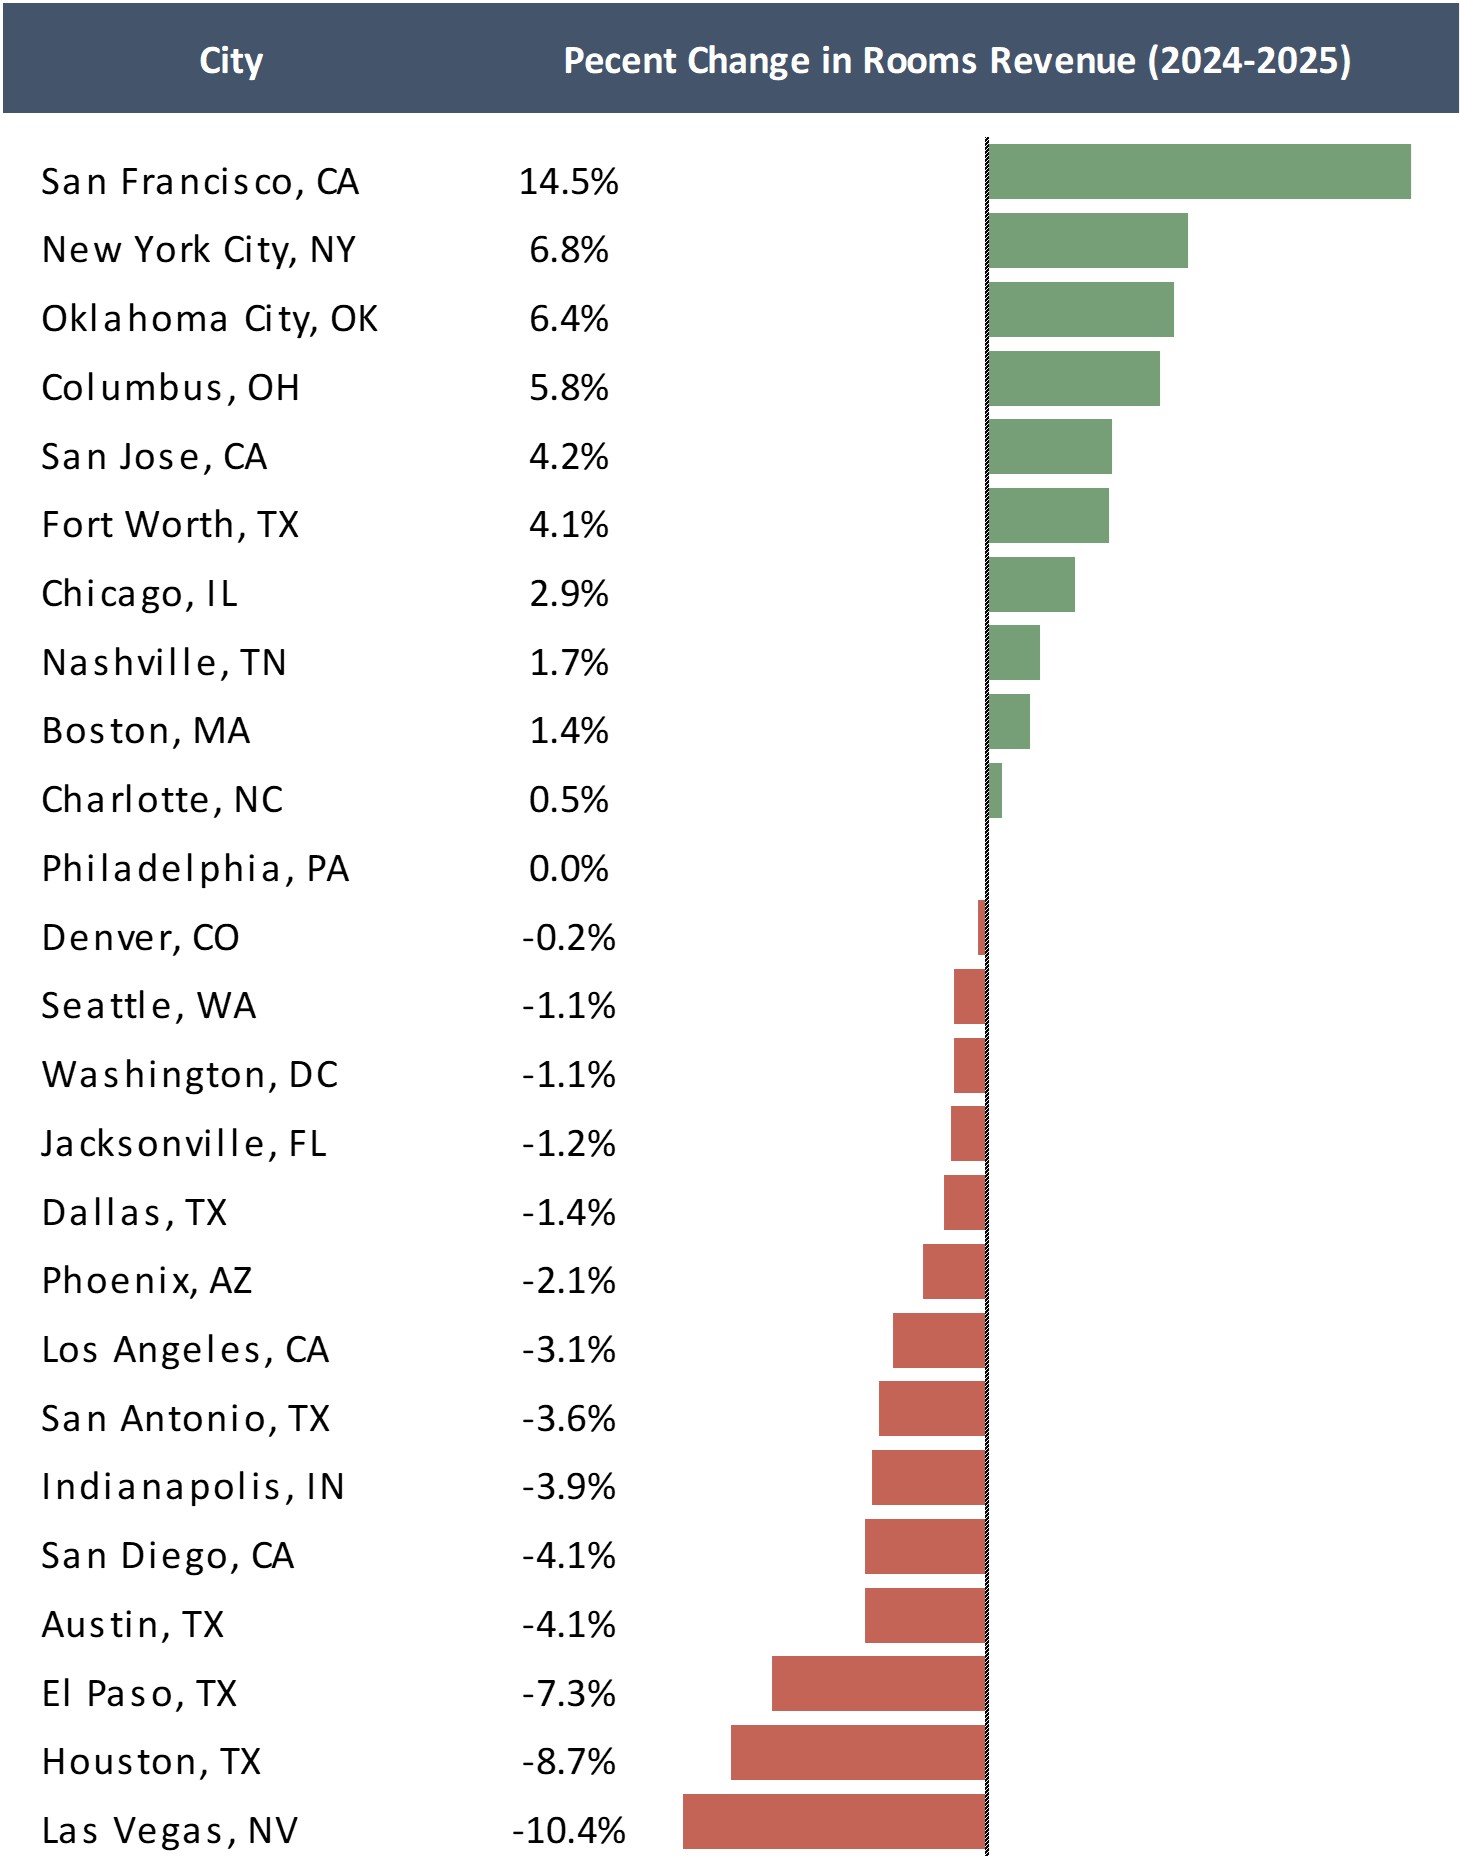
Occupancy declined in 2025 compared to 2024, with ADR growth also slowing due to reduced leisure travel and greater consumer price sensitivity, resulting in a slight decline in RevPAR. Year-to-date 2026 data through August shows a rebound, with occupancy up approximately 1.4% and ADR up approximately 3.4%, driving RevPAR growth of nearly 5%. The following figure shows the year-over-year change in room revenue for the top 25 major U.S. markets as measured by city population. We compared 2024, 2025, and year-to-date 2026 rates of change in room revenue.

Top 25 US Lodging Markets: Year-Over-Year Growth of Rooms Revenue
Source: CoStar

Room revenue performance diverged sharply across the top 25 U.S. markets from 2024 to 2025. Ten markets posted gains, Philadelphia was flat, and the remaining 14 markets recorded declines. San Francisco led all markets with a 14.5% increase in room revenue, well ahead of New York City (6.8%), Oklahoma City (6.4%), and Columbus (5.8%). At the other end of the range, Las Vegas (-10.4%), Houston (-8.7%), and El Paso (-7.3%) saw the steepest declines. With more than half of the top 25 markets reporting lower room revenue, these results point to a softening of the revenue base on which lodging taxes are levied, and lodging tax collections in many major markets are likely to flatten or decline in the near term.

Hotel room revenue is the base on which most lodging taxes are levied, so the size of each market's room revenue, along with its tax rate, determines the scale of its lodging tax collections. CoStar reports room revenue net of taxes, so the figures below reflect pre-tax room sales and exclude the lodging taxes collected on them. Short-term rentals also generate lodging taxes in nearly all jurisdictions, but this impact is not captured in the CoStar data.

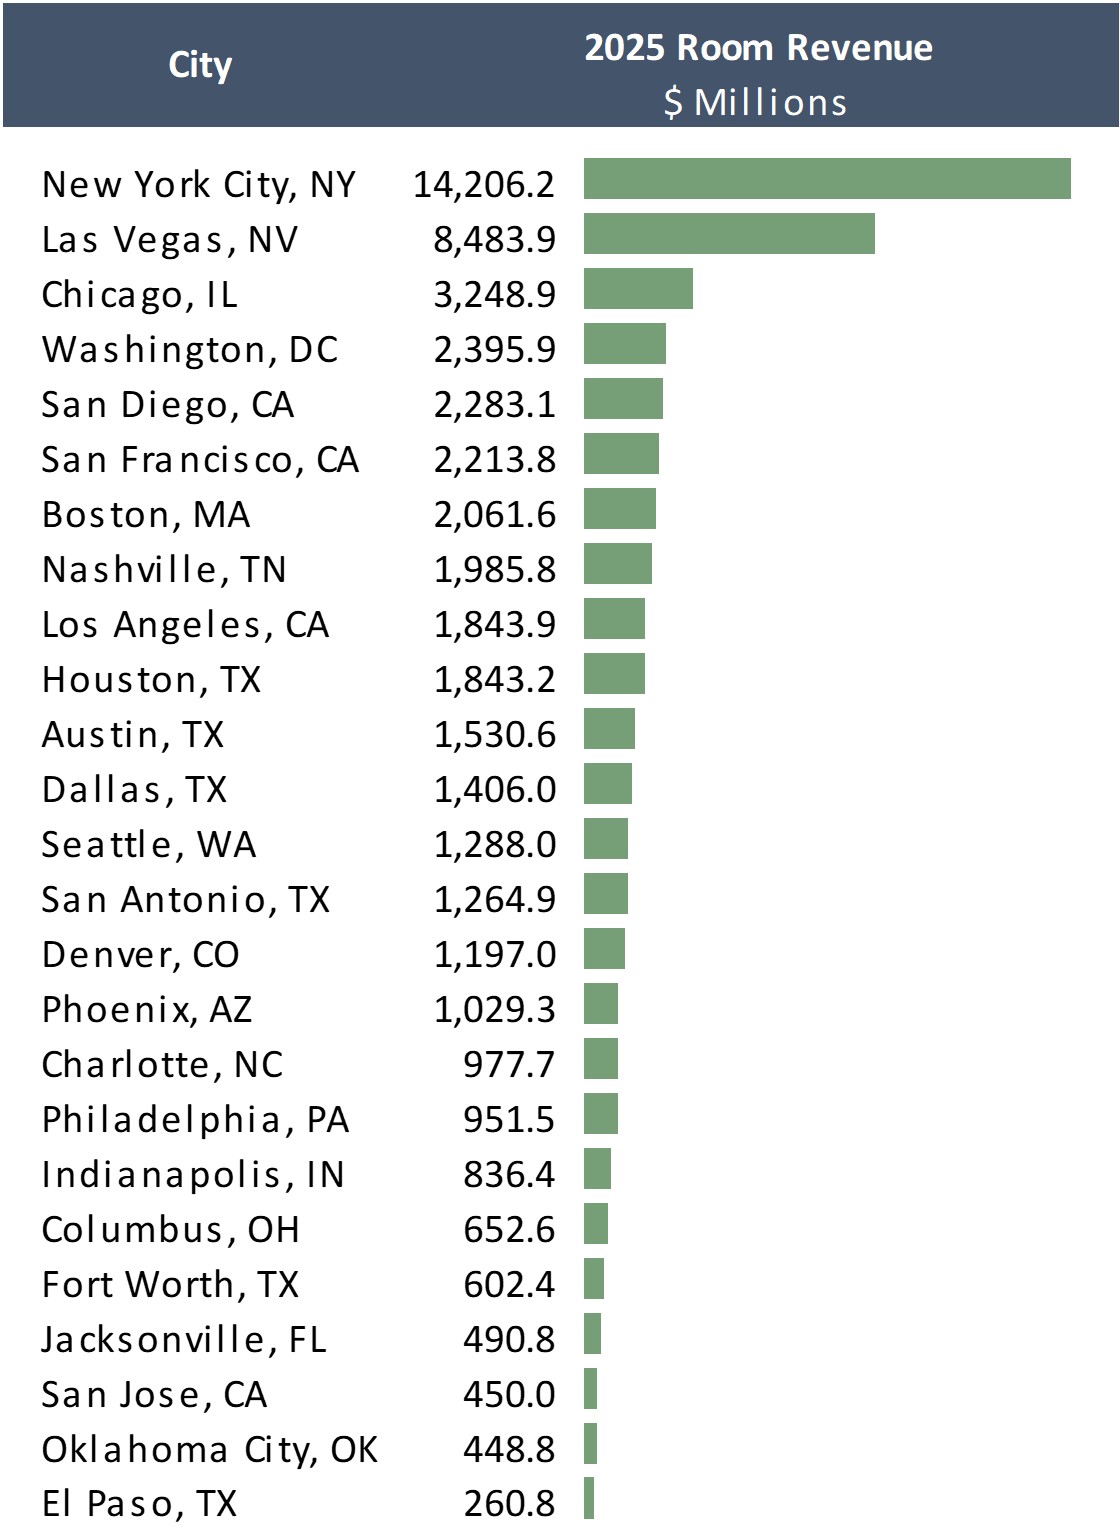
The following figure shows 2025 room revenue for the top 25 U.S. lodging markets.

Top 25 US Lodging Markets: 2025 Room Revenue
Source: CoStar

The top 25 markets generated approximately $54.0 billion in room revenue in 2025, but that revenue is highly concentrated. New York City and Las Vegas stand well apart from the rest, together accounting for more than 40% of the total, and New York City alone generated more than four times the revenue of Chicago, which ranks third in room revenue. Most of the remaining markets fall within a narrower band of $1 billion to $3 billion, while the nine markets below $1 billion together contribute only about a tenth of the total.

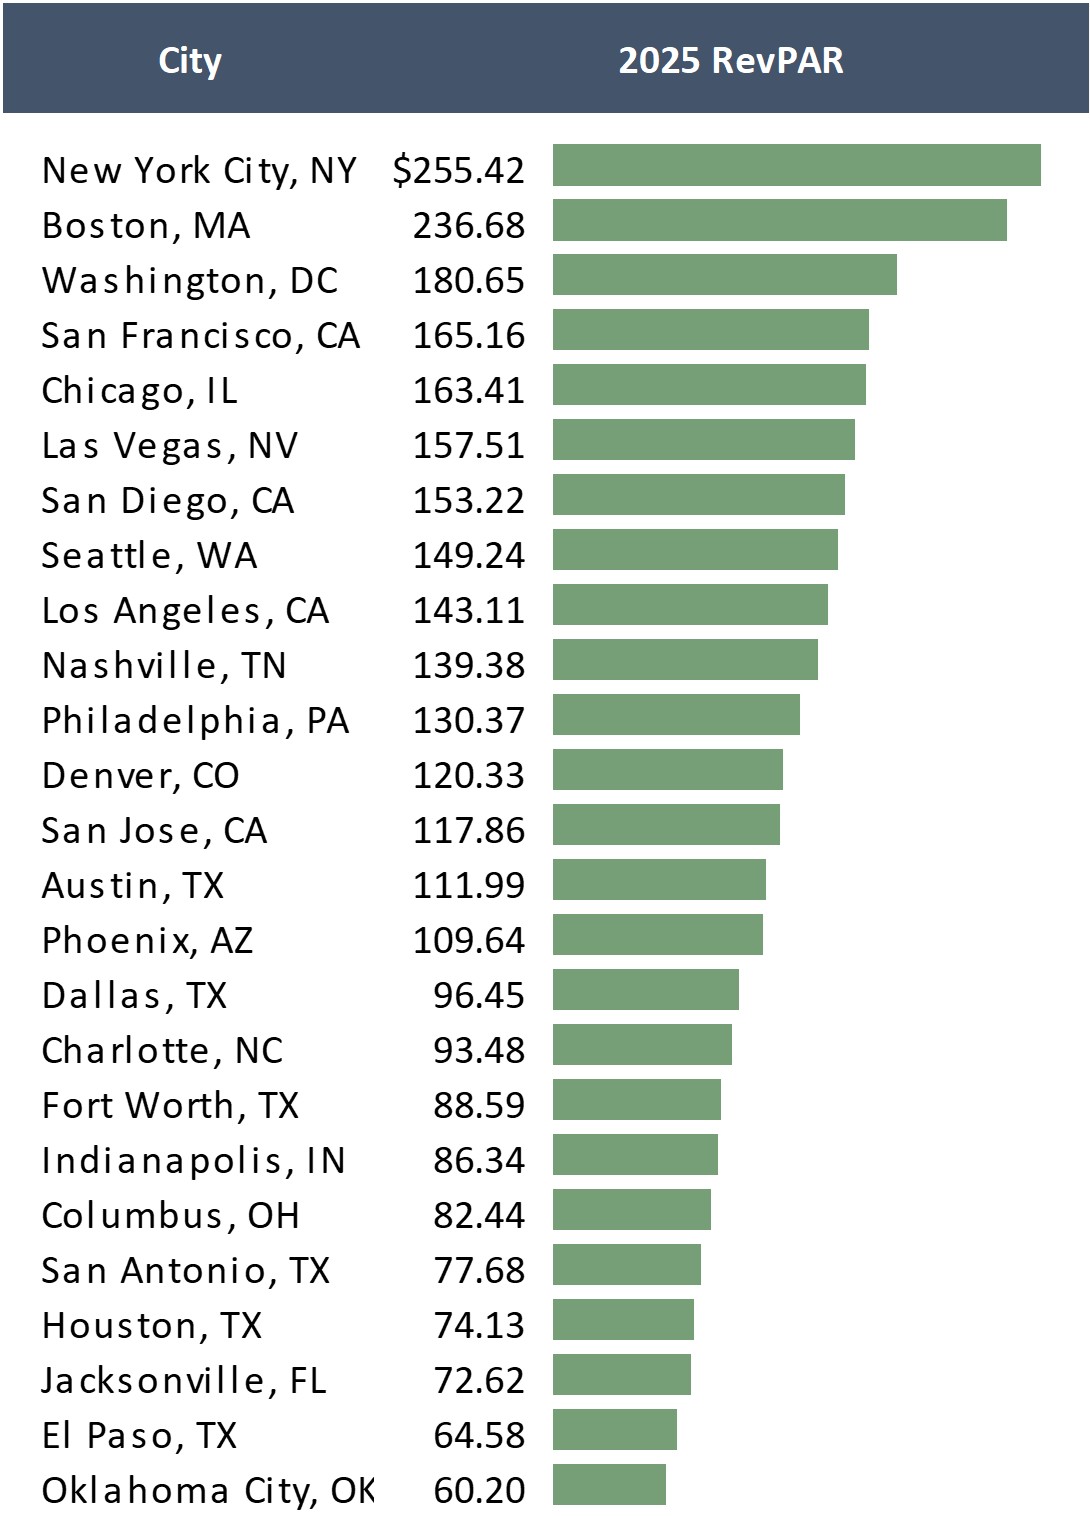
While room revenue reflects the overall size of a market, RevPAR measures how much revenue each available hotel room generates, combining occupancy and average daily rate into a single measure of performance. Comparing RevPAR across markets shows which destinations earn the most from each room, regardless of how many rooms they have. The following figure shows 2025 RevPAR for the top 25 U.S. lodging markets.

Top 25 US Lodging Markets: 2025 RevPAR
Source: CoStar

RevPAR varied widely in 2025, with New York City and Boston leading at more than $200 per available room, about four times the level in Oklahoma City. RevPAR rankings often differ from room revenue rankings. Las Vegas and Houston rank among the top ten in room revenue but lower in RevPAR, reflecting the scale of their markets rather than performance per room. Boston shows the opposite, ranking second in RevPAR but seventh in room revenue. These differences show that high-performing markets such as Boston generate strong lodging tax collections from each room, while high-volume markets such as Las Vegas and Houston produce large collections through the sheer size of their hotel markets.

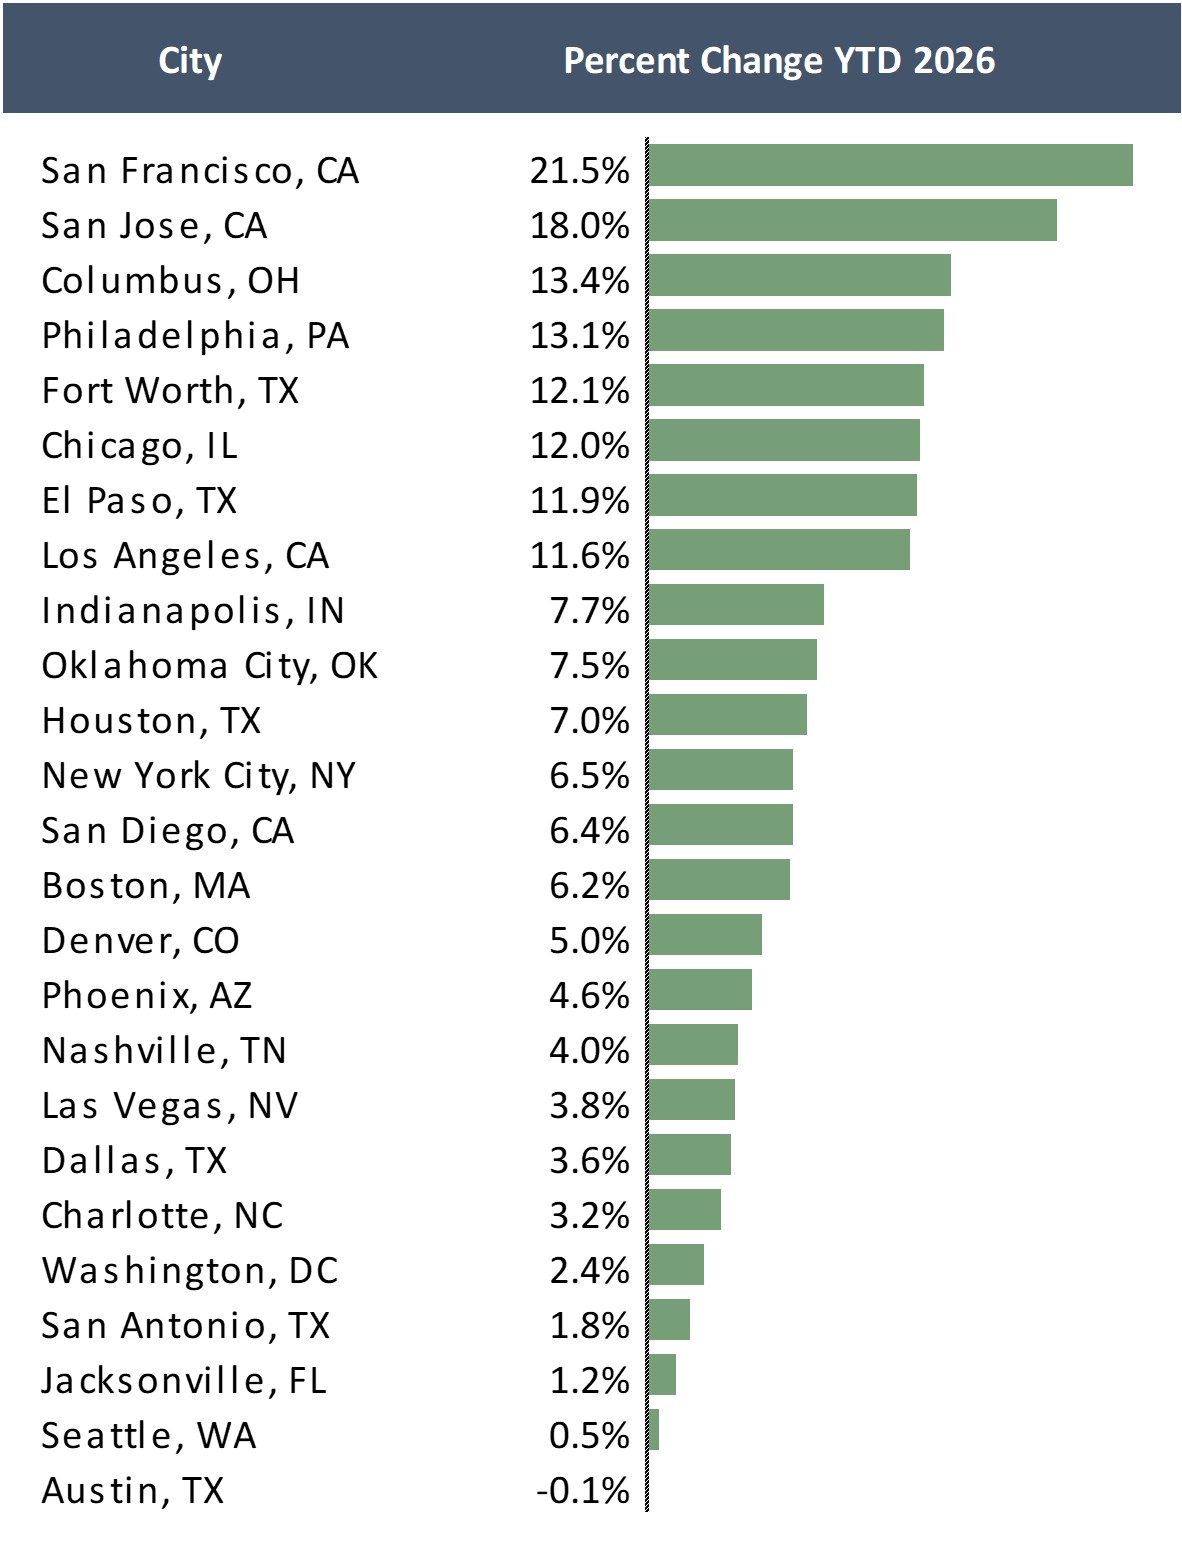
While the previous figures reflect full-year 2025 performance, 2026 year-to-date data provides an indication of where the lodging tax base is heading. The following figure shows the year-to-date percent change in RevPAR for the top 25 U.S. lodging markets in 2026 compared with 2025.

Top 25 US Lodging Markets: 2026 RevPAR Outlook
Source: CoStar
 
Hotel performance has strengthened broadly in the first eight months of 2026. Combined year-to-date room revenue across the 25 markets rose 7.8% compared with the same period in 2025, to approximately $37.3 billion, and RevPAR increased in all but one market. San Francisco and San Jose led with gains of 21.5% and 18.0%, lifted by AI and technology conventions, along with Super Bowl LX and the FIFA World Cup in Santa Clara. Austin was the only market to decline, largely due to the closure of its convention center for redevelopment, which removed the hotel demand generated by citywide conventions. New York City and Las Vegas, the two largest revenue markets, experienced more moderate growth. Overall, broad-based RevPAR growth points to a recovering lodging tax base after a softer 2025, although modest gains in several large markets may slow the recovery in total collections.

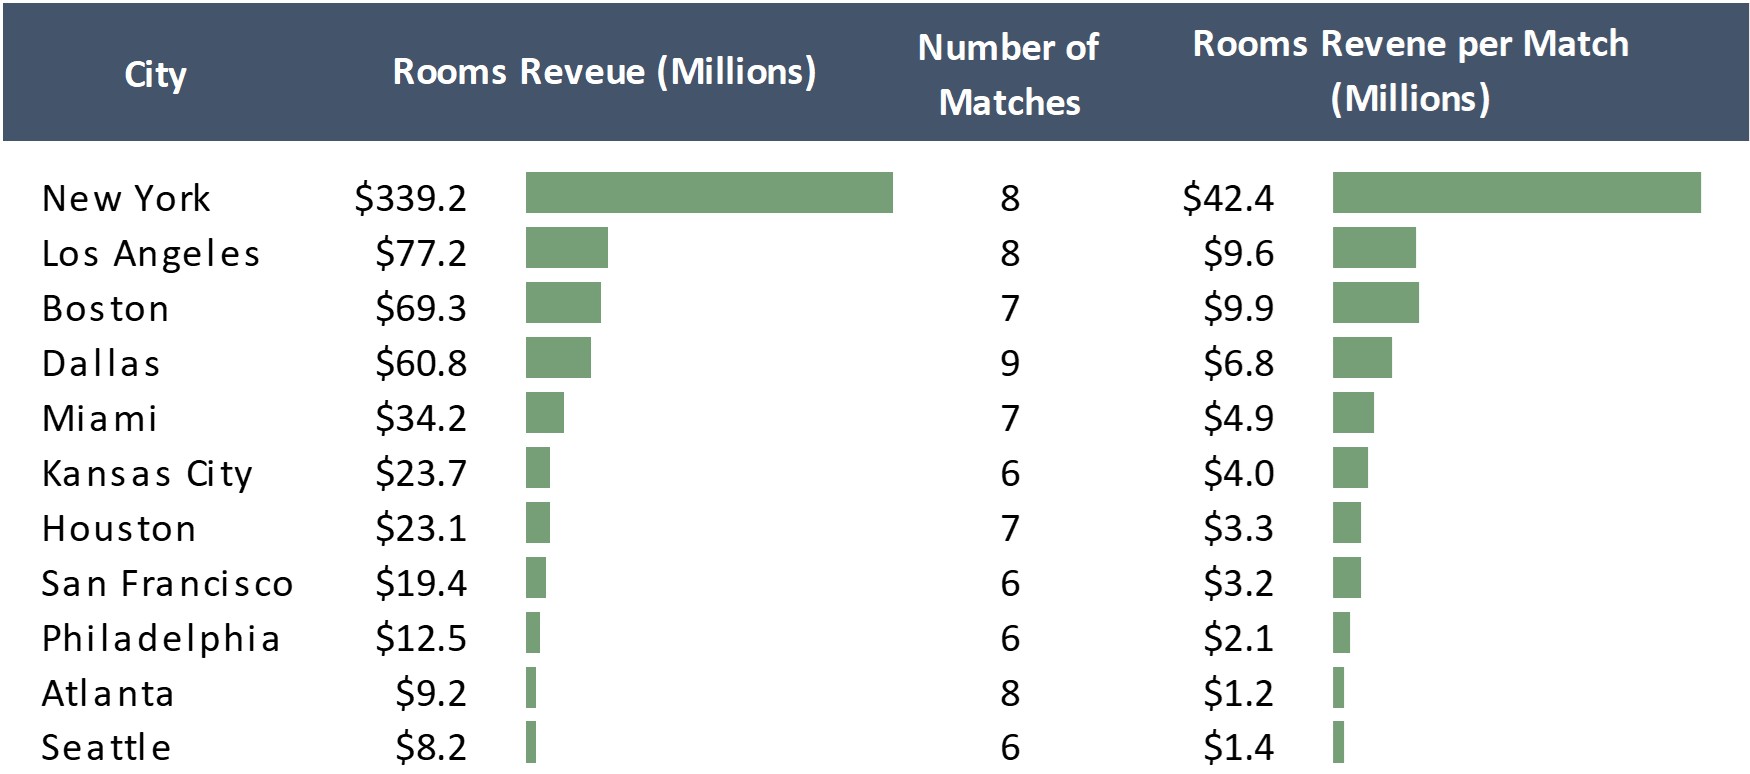
Many of these markets hosted 2026 FIFA World Cup matches, which likely contributed to the widespread RevPAR growth through August 2026.[1] The following figure shows the estimated rooms revenue impact in each U.S. host market.
 
Rooms Revenue Changes during FIFA Match Weeks
Source: CoStar data and HVS Analysis

The 2026 FIFA World Cup generated a substantial impact on hotel performance across its eleven U.S. host markets, producing an estimated $680 million in incremental rooms revenue overall. New York captured by far the largest share at $339.2 million, or $42.4 million per match. On a per-match basis, Boston ranked second at $9.9 million, slightly ahead of Los Angeles. Kansas City's performance was also notable relative to its market size, out-earning larger markets such as Houston and San Francisco on both a total and per-match basis. Because no event of comparable scale is scheduled for 2027, these markets will be measured against an elevated 2026 base. As a result, growth in lodging tax collections may fall below historical trends in 2027.

Economic Uncertainty

This report was prepared during a period of significant uncertainty, marked by multiple changes in U.S. policies that have impacted both the domestic and global economies. Any subsequent change to these perspectives or information could affect the future growth of lodging tax revenues.

Throughout 2025 and into 2026, shifting trade policy and litigation over the legality of the administration's tariffs created widespread uncertainty surrounding how the U.S. and global economies may respond.[2] Since late February 2026, the conflict with Iran has pushed energy prices higher, adding to inflationary pressure and prompting the Federal Reserve to raise interest rates. Areas of concern include rising energy and borrowing costs, which, combined with inflation, would further increase the cost of doing business and continue to impact the pipeline for new development. Tighter household budgets could also affect domestic travel, including both transient and group activity. In addition, the U.S. government’s immigration and visa policies may result in a shortage of hospitality workers.

Geopolitical concerns have influenced global travel to the US. Tourism Economics estimates that international overnight visits to the U.S. fell 5.7% in 2025, driven largely by a 25.7% decline in visits from Canada, and expects ongoing policy uncertainty to limit the recovery in 2026.[3]

Until more clarity emerges, the near-term outlook remains uncertain due to the factors mentioned above. Persistent inflation, higher interest rates, and weakening consumer confidence remain key concerns. Over the long term, the hospitality industry has proven to be extraordinarily resilient following past “shock” events and downturns such as 9/11, the Great Recession, and the COVID-19 pandemic. Despite temporary declines, the industry’s performance has consistently recovered and continued to grow. Thus, we are confident the industry will prove to be similarly resilient following the current period of uncertainty.

Labor Force

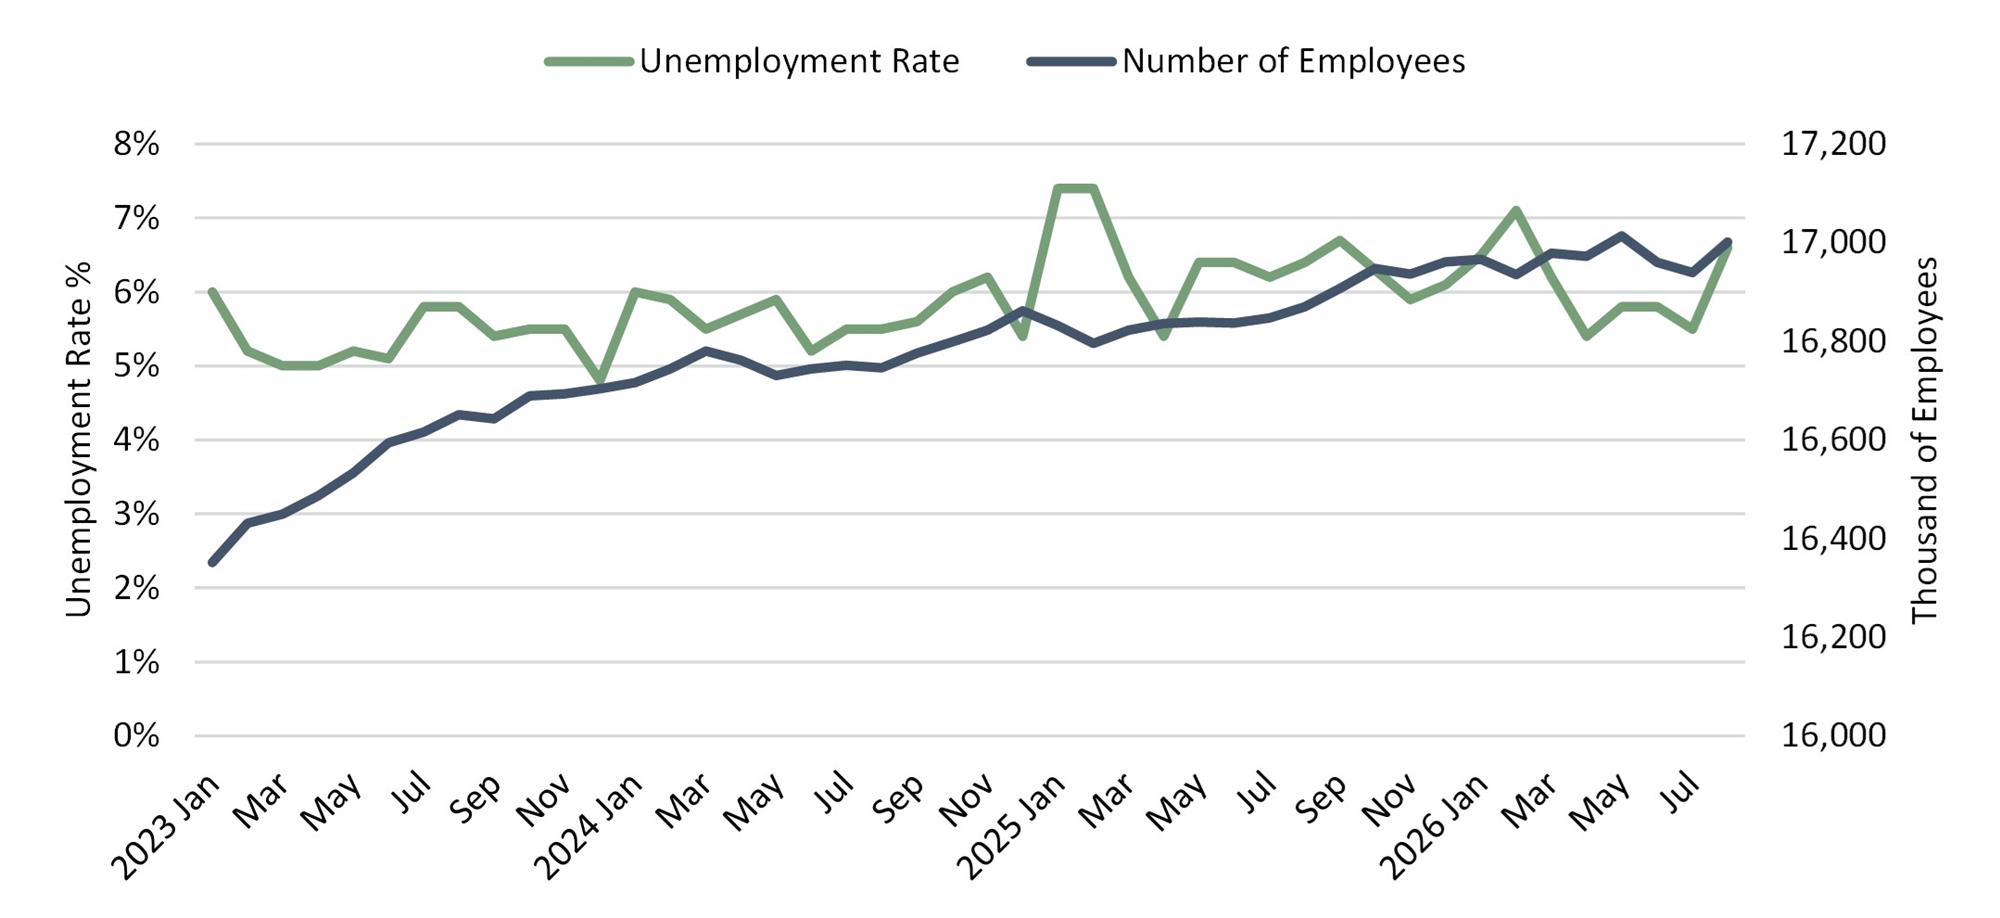
Since 2023, employment in the hospitality and leisure sector has grown modestly before leveling off in mid-2025, continuing to support the industry's capacity to meet lodging demand. The graph below compares the number of employees in hospitality with the unemployment rate.

Hospitality and Leisure Sector Employment (Total US)
Source: Bureau of Labor Statistics

After growing from 2023 through mid-2025, employment in the hospitality and leisure sector has remained largely flat at approximately 17.0 million since mid-2025. Unemployment in the sector has remained between 5% and 7.5% since January 2025. A stable workforce allows hotels to meet current demand, though limited employment growth may constrain the industry's capacity to expand as lodging demand, and the lodging tax base, recovers in 2026.

Imposition of Lodging Taxes

Lodging taxes are typically ad valorem taxes (levied as a percentage of value) on short-term[4] overnight stays at hotels, motels, bed-and-breakfasts, and other lodging accommodations. Lodging taxes levied by state and local governments share common characteristics but are known by various names, including hotel occupancy tax, hotel-motel tax, room tax, bed tax, transient occupancy tax, tourism improvement tax, and others. States authorize the imposition of lodging taxes, except in home rule cities.[5] States may tax lodging as a part of a general sales and use tax, a specific lodging tax, or both. For most lodging taxes, state legislation defines the tax base, determines who is exempt from the lodging tax, and establishes collection procedures. State, county, and local governments also impose lodging taxes, which may distribute tax revenues to their general, special revenue, or debt service funds. In many cities, state and municipal governments have formed special districts to levy additional lodging taxes on hotels within a defined geographic area. Different districts within a city may have varying rates of lodging taxes. Certain state and local governments also impose excise taxes on lodging at a fixed amount per unit of sale, such as a $1.00 per-room-night fee for furnishing a hotel room.

From a political perspective, lodging taxes may be easier to impose than other taxes because visitors who use lodging accommodations are not constituents of the local municipalities. Typically, hotel operators collect the tax from guests and receive a small administrative fee of one or two percent of collections.

While the tax's legal incidence may fall on the consumer, the economic burden of the lodging tax is shared by both lodging providers and their guests. A lodging tax raises the price of lodging accommodations. Depending on the elasticity of the supply and demand for lodging, the hotel manager may be unable to increase their room rates enough to compensate for paying the full amount of the tax. Since the elasticity of supply and demand changes depending on market conditions, the true incidence of a lodging tax varies as market conditions change. This study does not attempt to estimate the economic incidence of lodging taxes.

Hotel owners are often willing to cooperate with local governments to impose lodging taxes dedicated to tourism promotion and the construction of convention centers. For hotel owners, tourist-oriented public facilities and advertising serve as drivers of room demand. All hotels in a given market can benefit from programs that bring tourists and convention attendees to a city. Sponsoring these types of programs would be prohibitively expensive for any individual hotel. In the case of convention centers funded by a lodging tax, the hotels and individuals who benefit from the center pay for its construction and maintenance. Municipalities seek to benefit from visitor spending and the associated tax revenue generated by convention centers. By imposing lodging taxes, those who benefit pay for advertising, marketing, and sales efforts funded by lodging tax revenue.

Some states, particularly those with large tourism industries, prevent municipalities from depositing hotel tax revenue into their general funds. For example, Florida allows only a series of special-purpose taxes for tourist development. Texas requires local transient occupancy taxes to fund convention center development or tourism promotion.

Since the 1970s, lodging taxes have become commonplace across the country. Of the 150 largest U.S. cities examined in this study, more than 125 impose a dedicated tax, and all collect some form of taxation on hotel room revenue. In small suburban cities and major tourist destinations, lodging taxes have become a significant source of funding for economic development initiatives. This study aims to survey hotel tax implementation nationwide, providing information for those seeking to compare the structure and revenue capacity of lodging taxes across diverse markets.

Changes in Lodging Tax Rates

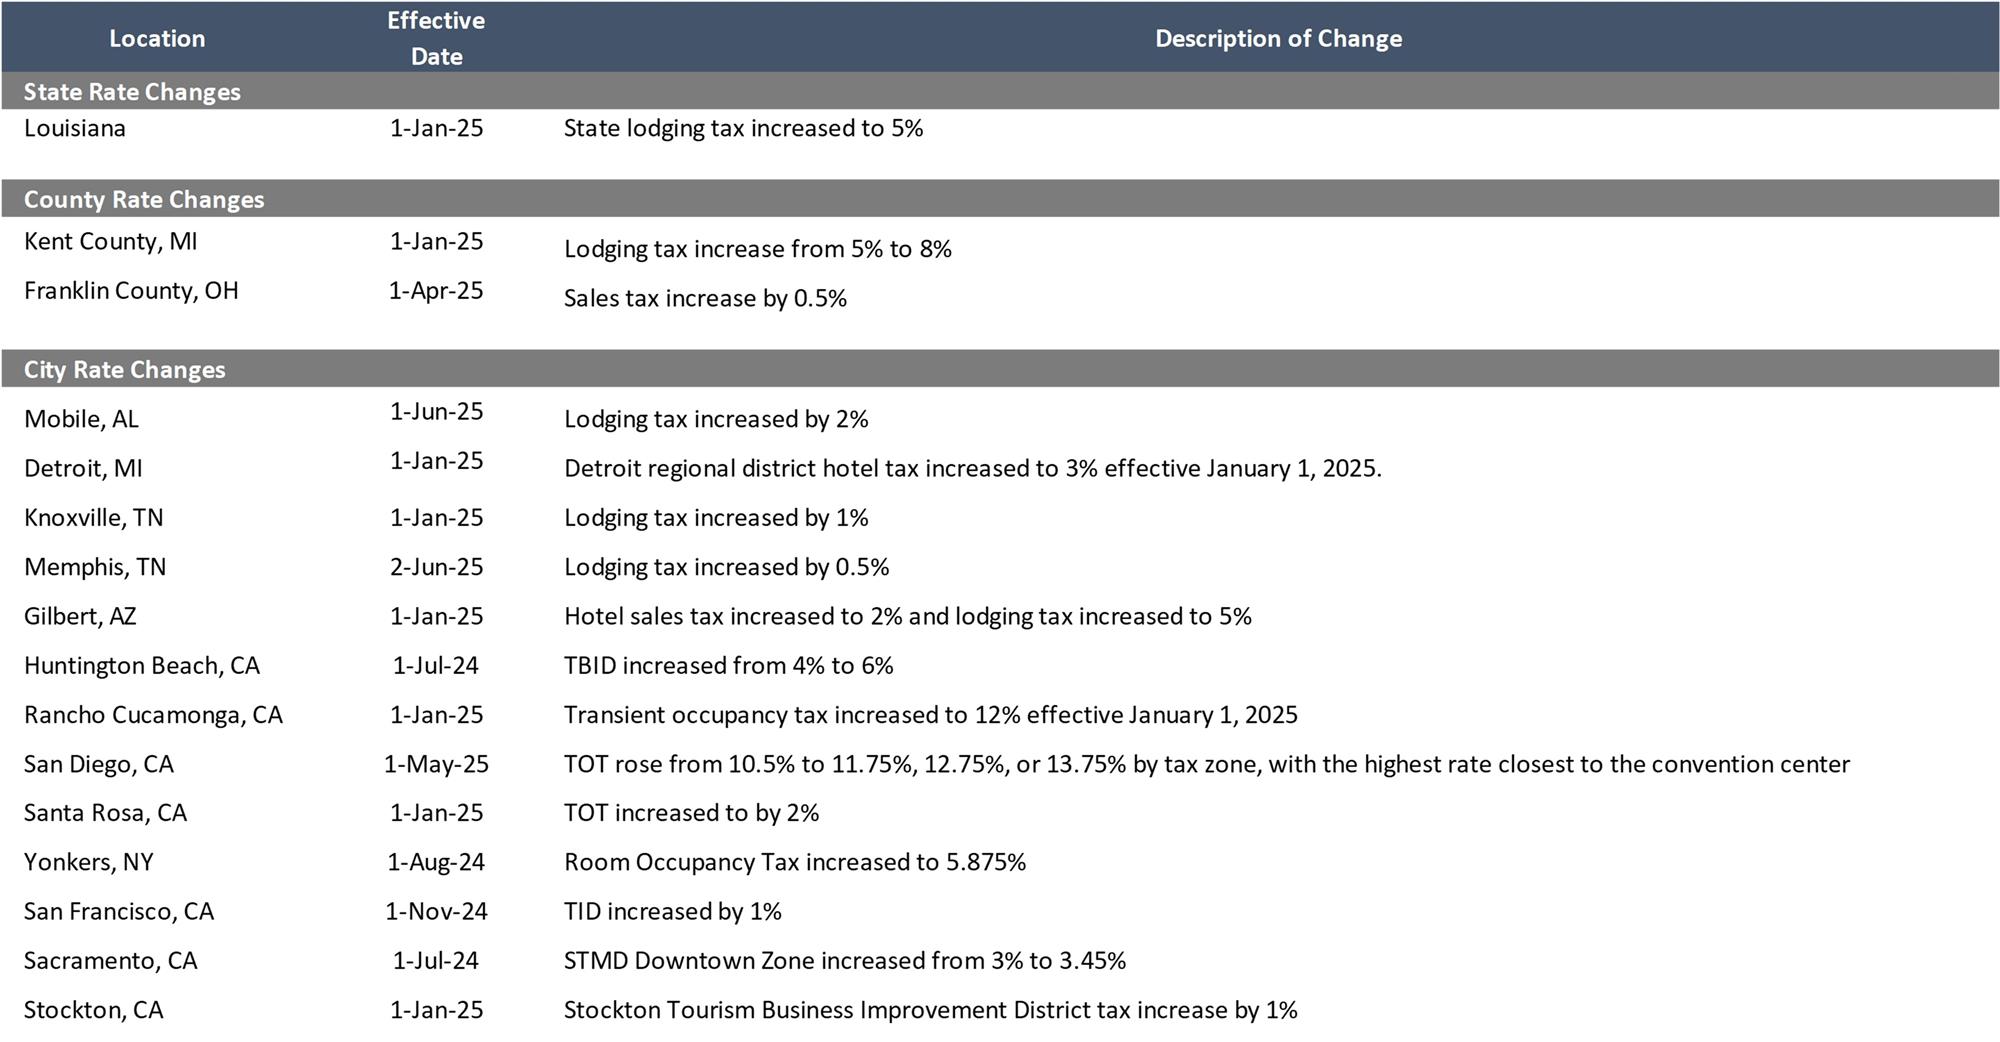
State, county, and local governments enacted several rate changes that took effect during fiscal year 2025. Recent changes in lodging taxes in cities include the following:

Recent Changes in Tax Rates

Source: Respective Jurisdictions
 
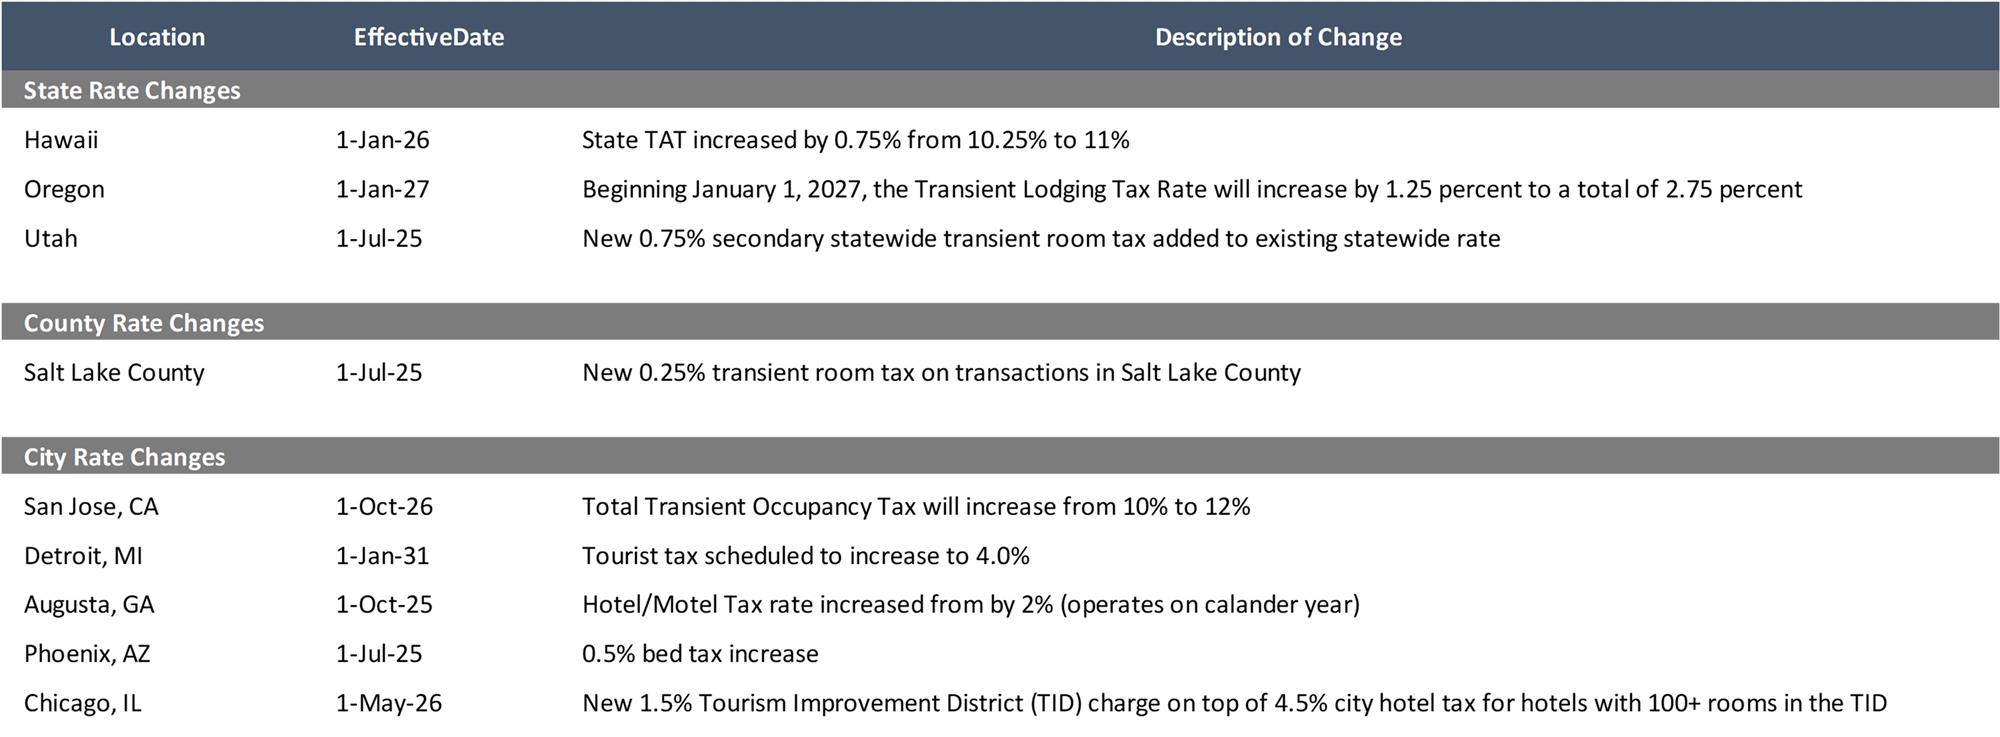
In addition to the 2025 county and local rate changes, we anticipate the following changes for the next several years.

Projected Changes

Source: Respective Jurisdictions

State Tax Rates

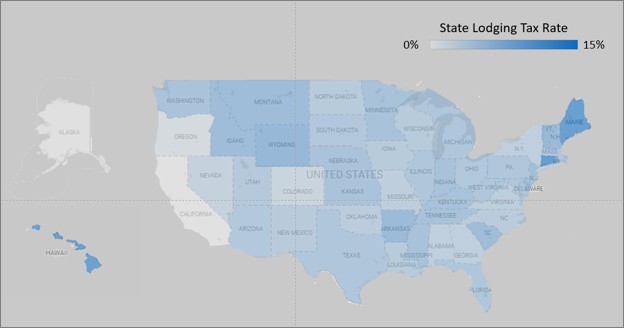
All but two states impose a sales tax, a lodging tax, or both on overnight transient accommodations. Municipal governments impose lodging taxes in two states (Alaska and California) that do not tax hotel lodging. Twenty-six states impose a separate lodging tax on hotel stays. In fifteen of these, the lodging tax is the only state tax on hotel rooms, while the other eleven also apply their general sales tax.

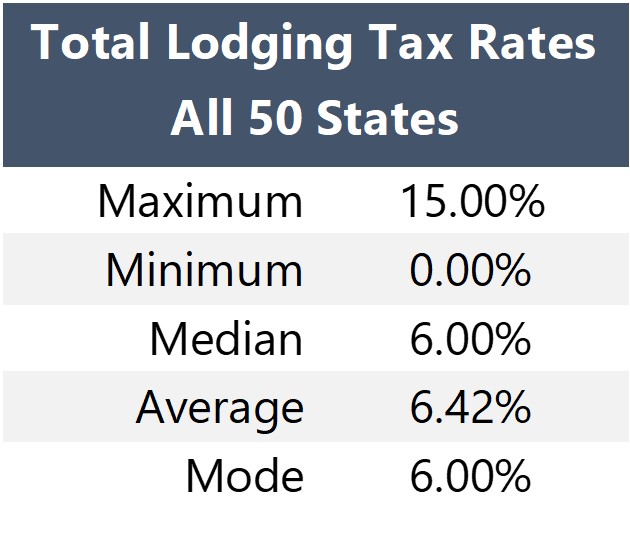
States with high lodging tax rates typically have more restrictions on imposing local lodging taxes. To illustrate, Connecticut has the highest statewide lodging tax rate at 15% but forbids all local authorities from imposing additional lodging taxes. On the other hand, Oregon imposes a low state lodging rate but does not restrict local taxes.

Source: Respective Jurisdictions

Appendix A, which can be found in the full download of the 2026 HVS Lodging Tax Report, presents a detailed description of each state’s lodging taxes and annual revenue collections.
 
State Lodging and Sales Taxes Imposed on Hotels
Source: HVS and Respective Jurisdictions
 
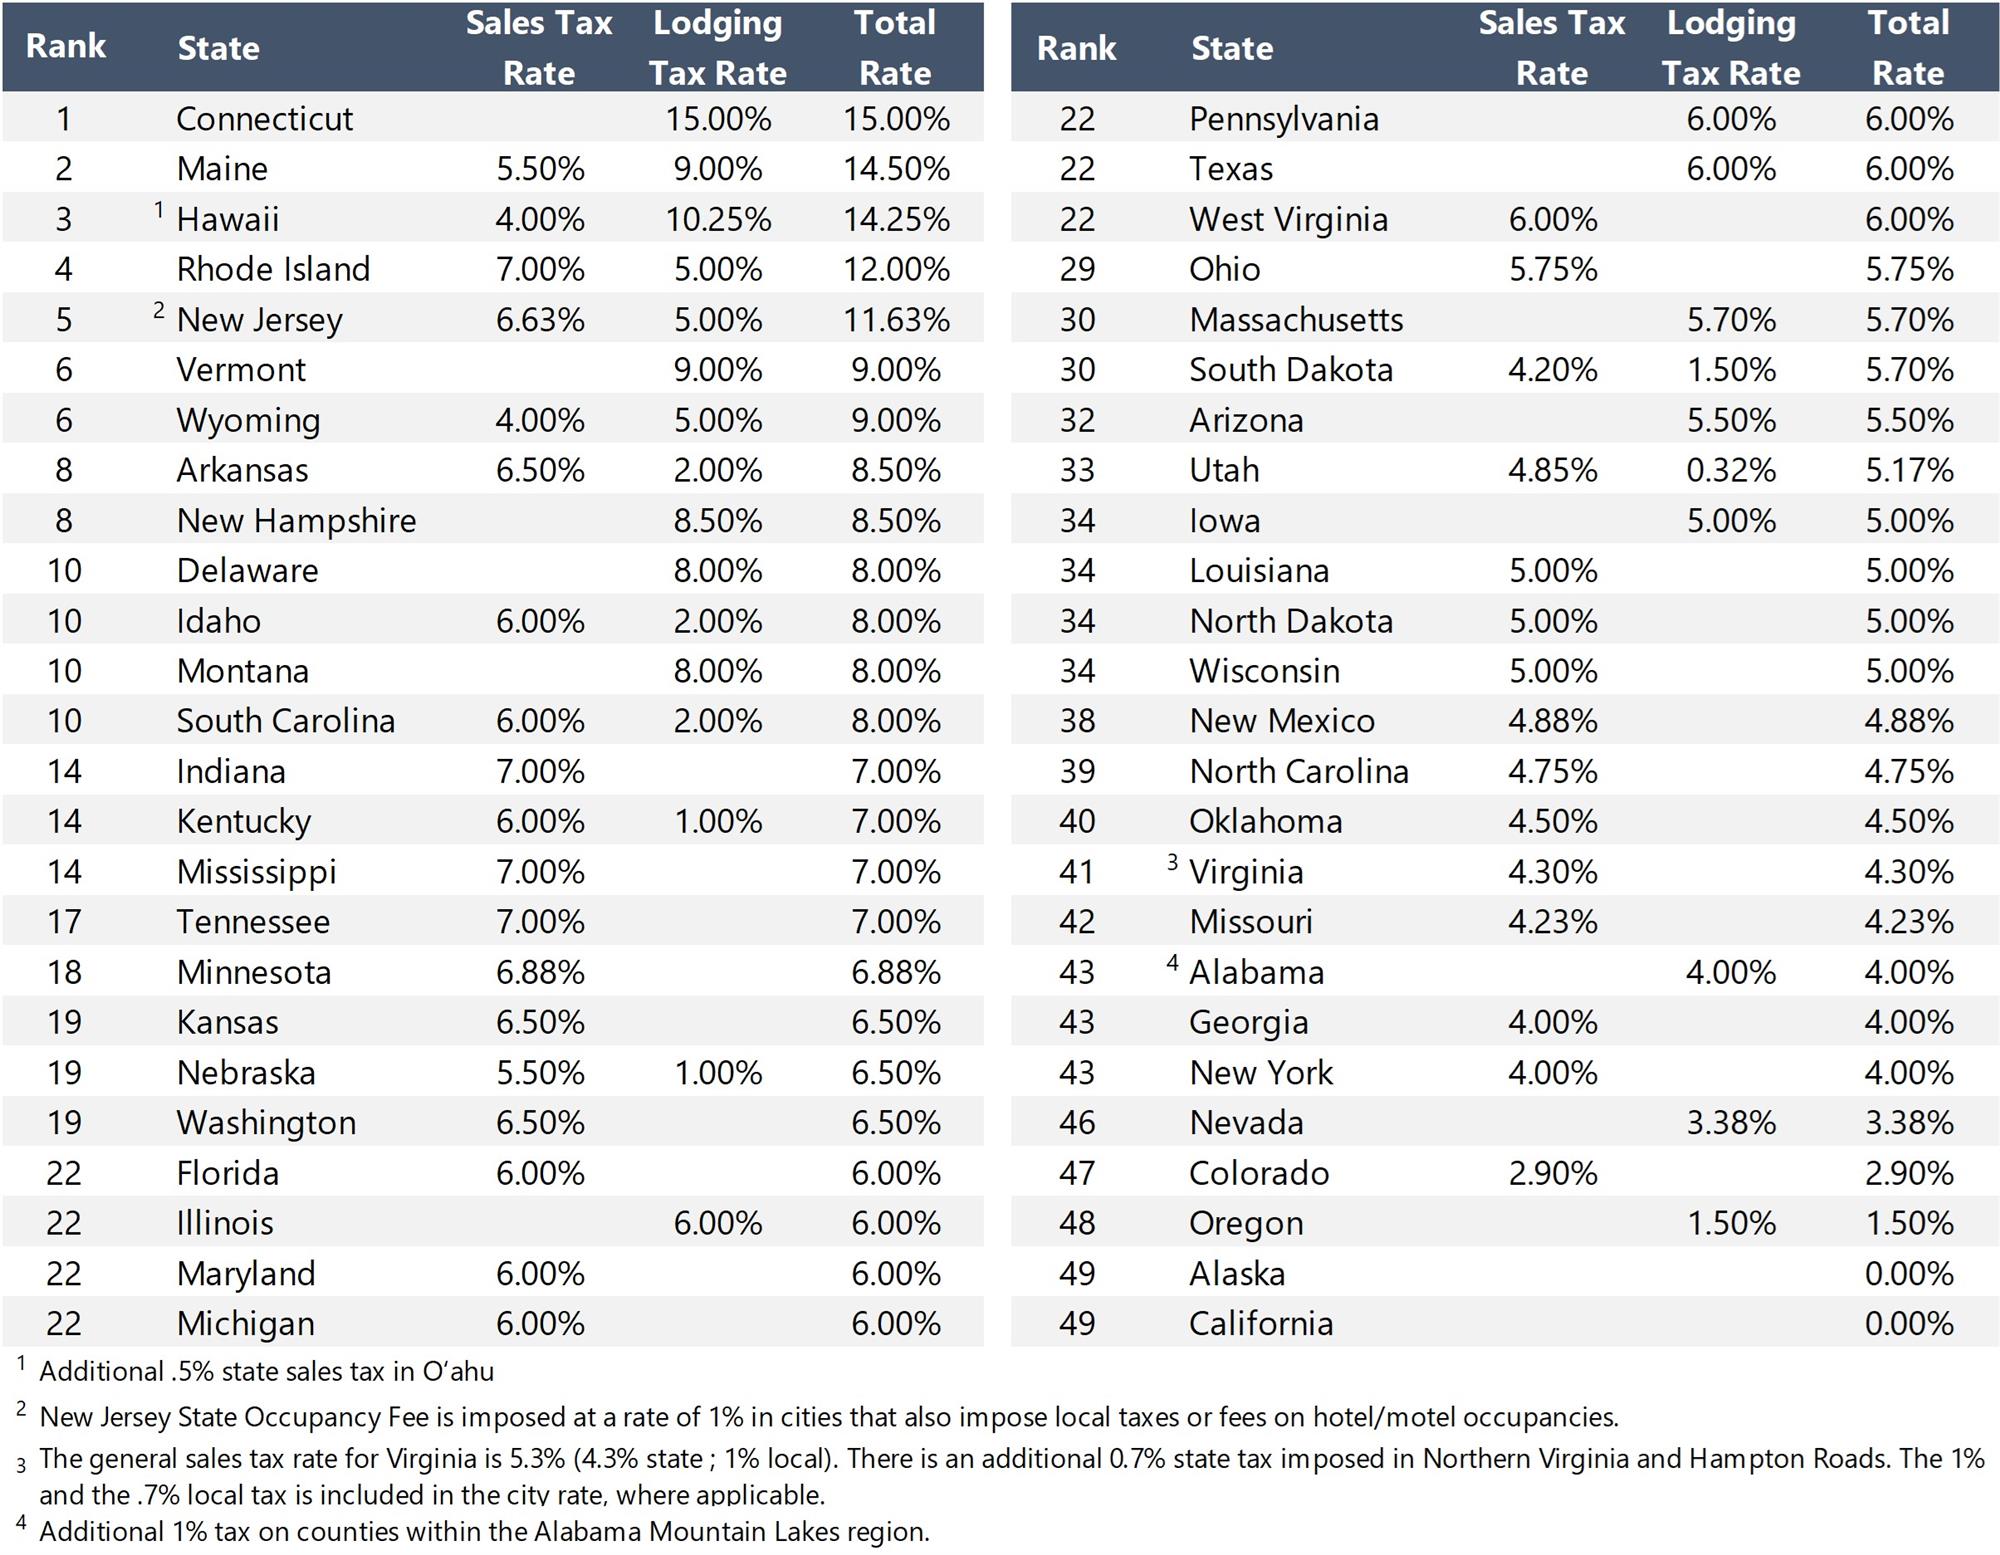
The following table lists the sales tax, lodging tax, and total tax rate levied on lodging accommodations. It ranks the 50 states by the total tax rate applied to lodging.
 
States Ranked by Total Ad Valorem Tax Rates on Lodging Accommodations 2025
Source: Respective Jurisdictions

State Lodging Tax Revenue

HVS analyzed annual state lodging tax revenues as reported in comprehensive annual financial reports, most of which use a modified accrual basis for revenue reporting. We recorded government estimates from budget reports in a few states where the final audited information was unavailable for fiscal year 2025. Government agencies sometimes provide annual lodging tax collection data instead of modified accrual data. Accrued revenues are recorded in the period in which the liability for tax payment occurs. Cash collections typically lag the period of liability by at least one month.

Depending on the size of their tax liabilities, taxpayers may remit payments on a monthly, quarterly, or annual basis. Administrative charges, payment of back taxes, and penalties may also affect the reported revenues, but the amounts are small. Only sales tax revenues in the accommodations sector were available in some states. Whereas lodging taxes are typically applied only to hotel room charges, sector-wide taxable sales might include other sources of taxable revenue, such as food and beverage revenue. We did not attempt to estimate the percentage of taxable sales due solely to overnight stays.

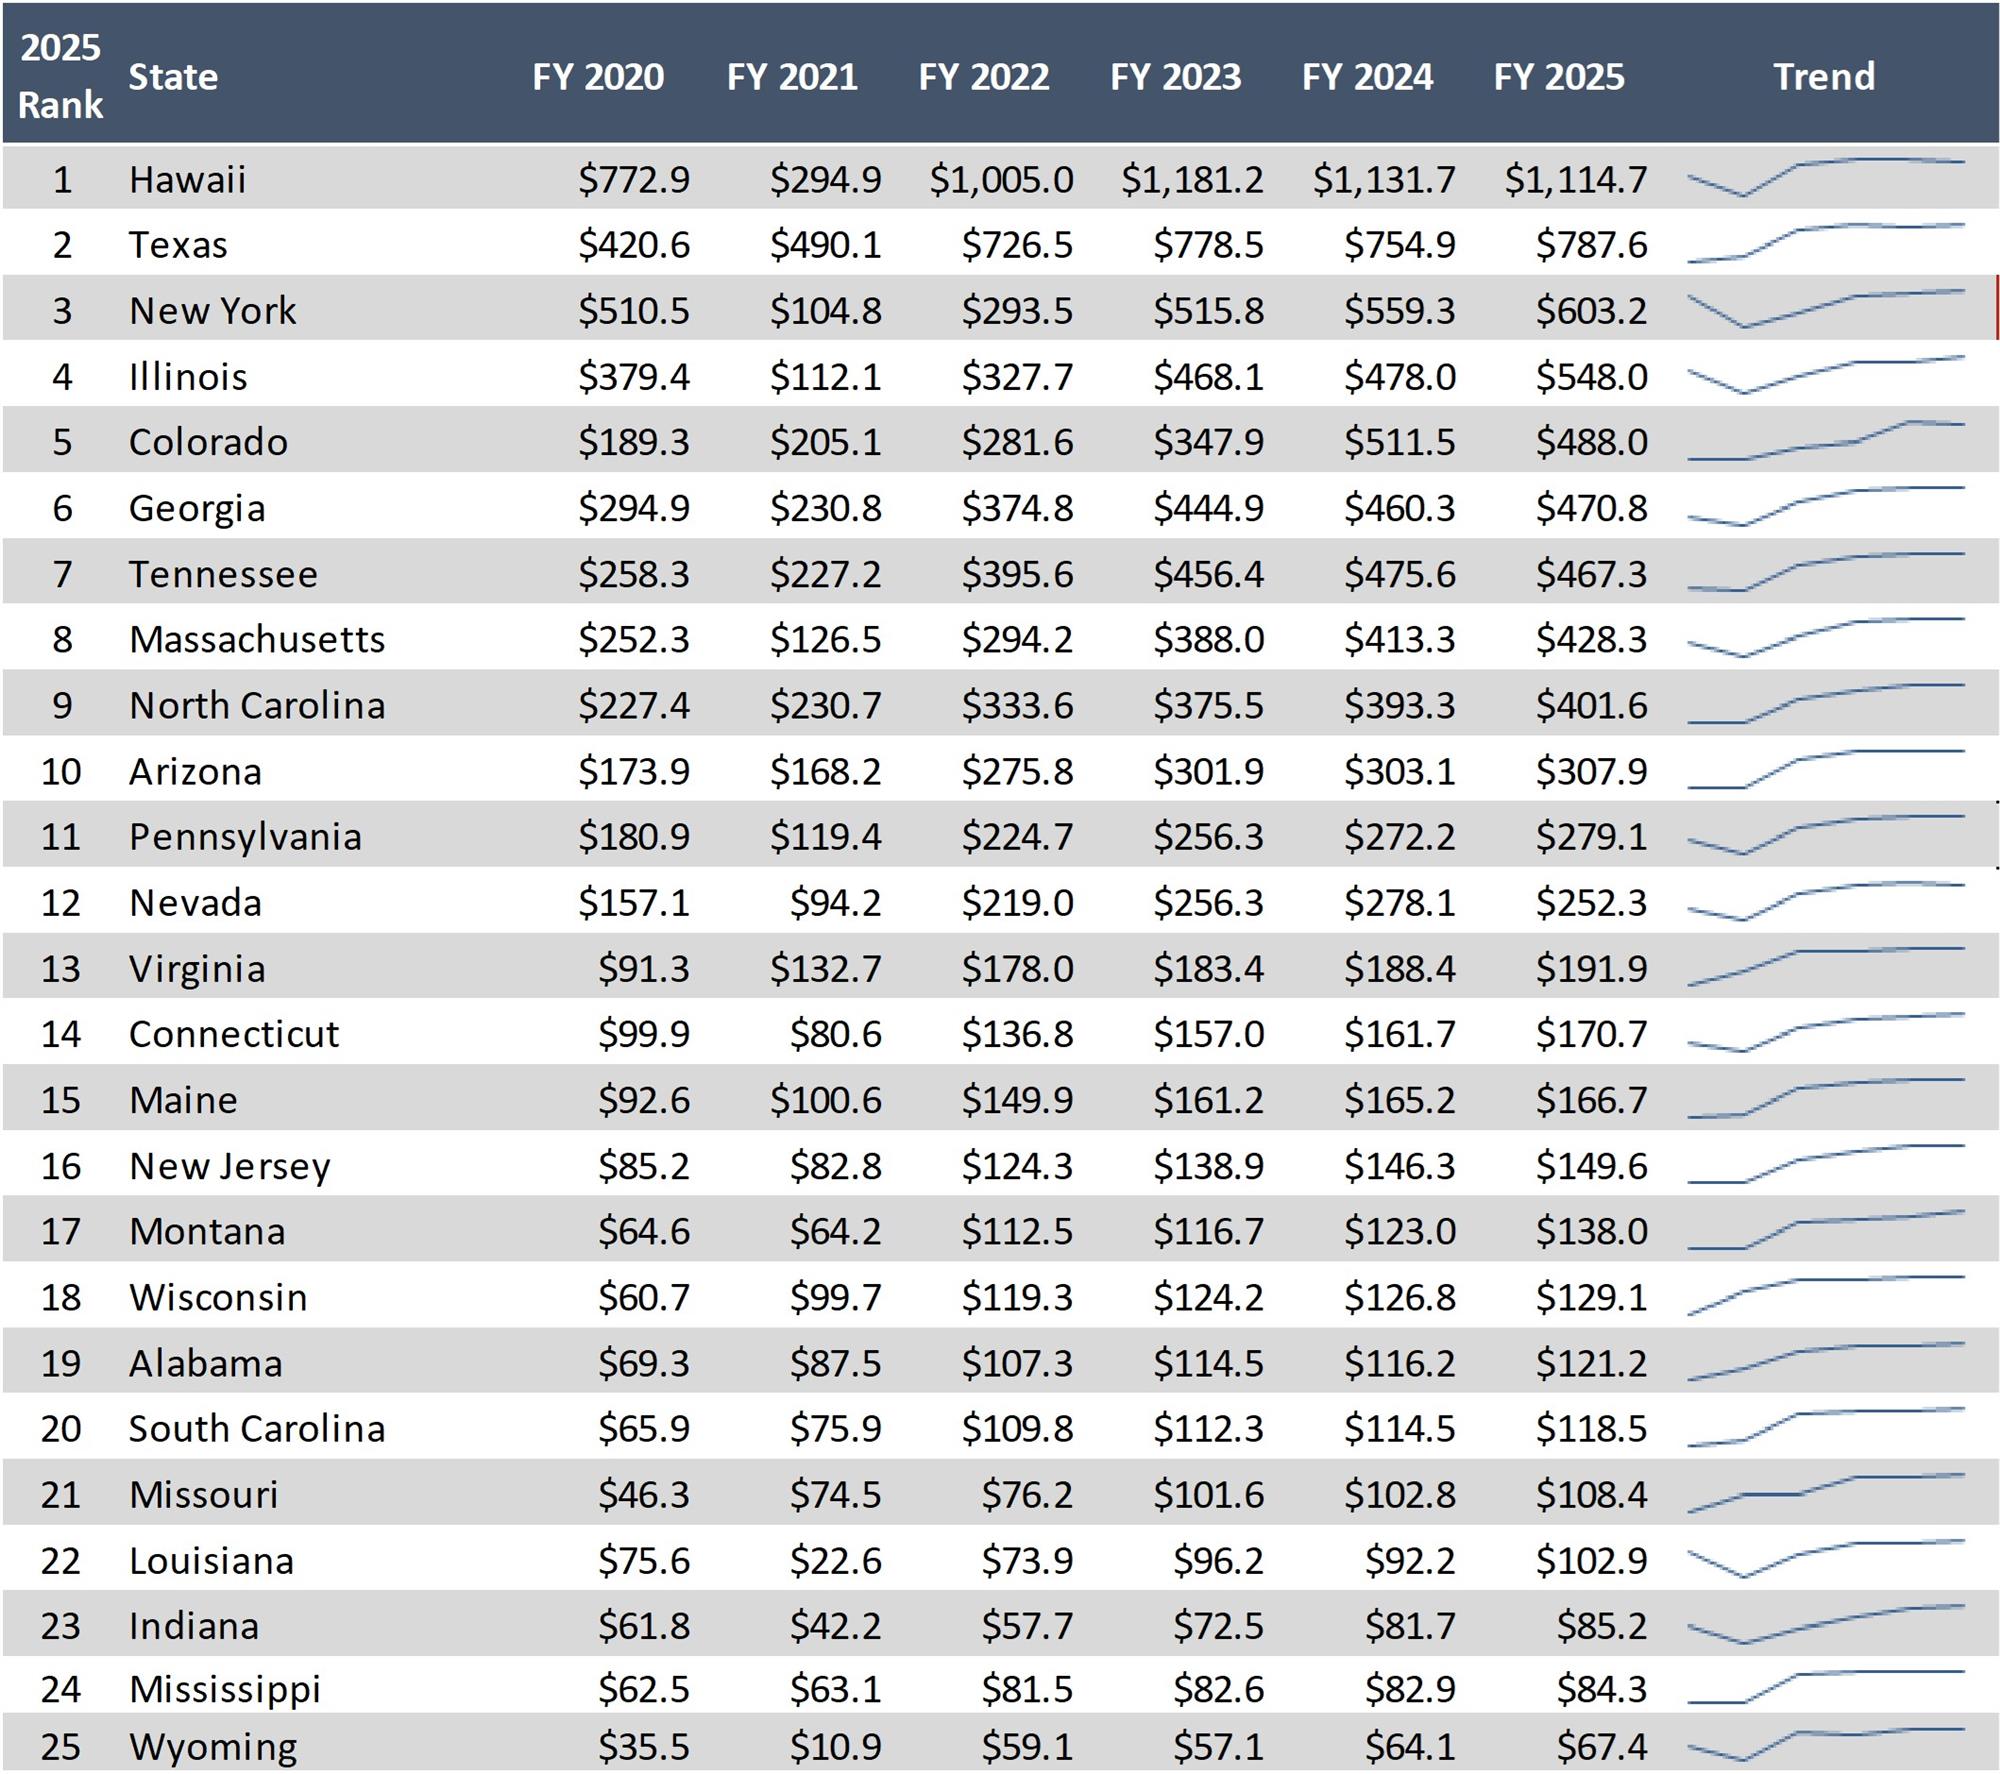
Among the states that collect lodging or sales tax on hotel rooms, total revenue increased by 2.5% in 2025 compared to 2024. This modest growth follows a 4.1% increase in 2024 and a strong 18.2% increase in 2023. The smaller increase in 2025 suggests that revenue growth is beginning to stabilize. Notably, not all states that reported lodging tax revenues in 2025 saw year-over-year increases, indicating that the strong growth of prior years has started to level off.

The following table presents a six-year history of lodging tax revenue for each of the twenty-five states that have imposed a dedicated lodging tax. Revenue reported from past years has been adjusted for inflation. Data is presented in millions of dollars, and the states are ranked by 2025 revenues.

Rank of States by 2025 Lodging Tax Revenues (millions)
Source: Respective Jurisdictions

Total Lodging Tax Rates

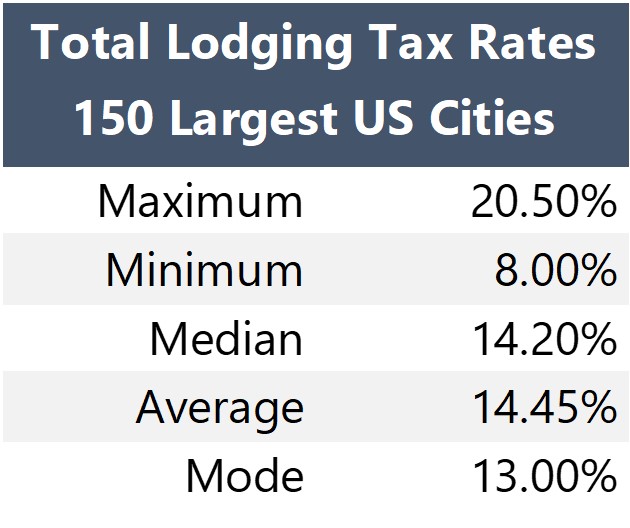
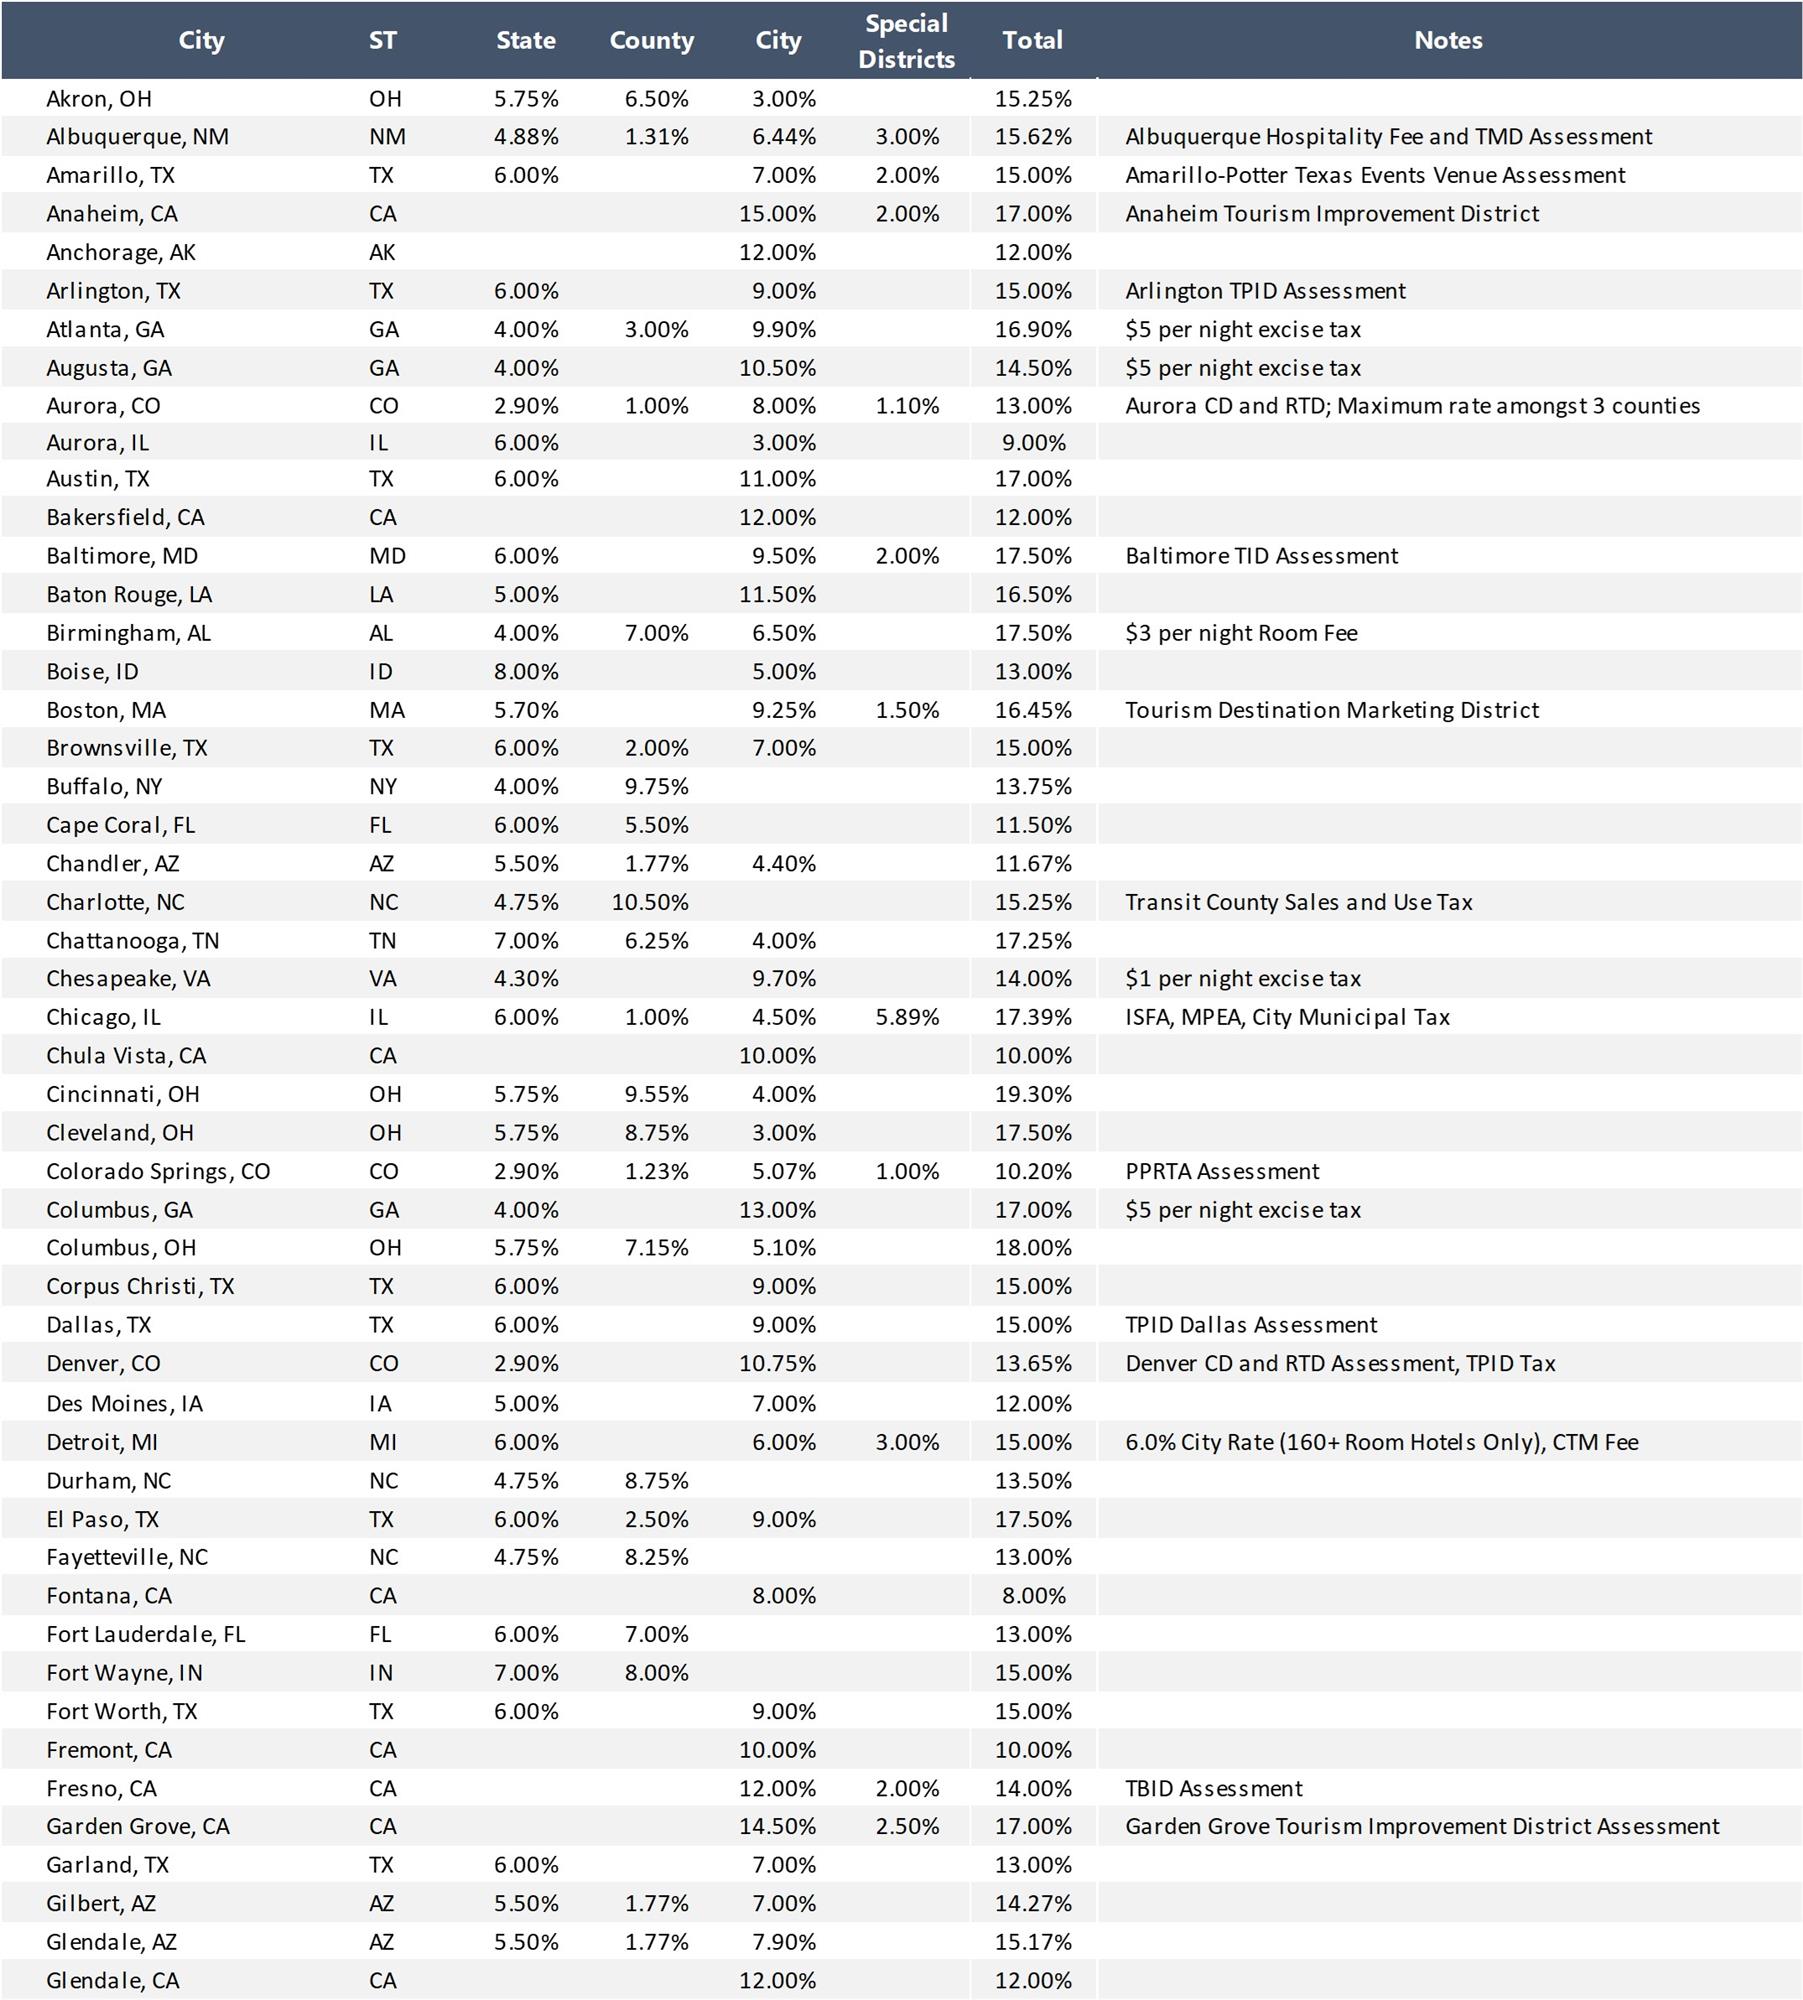
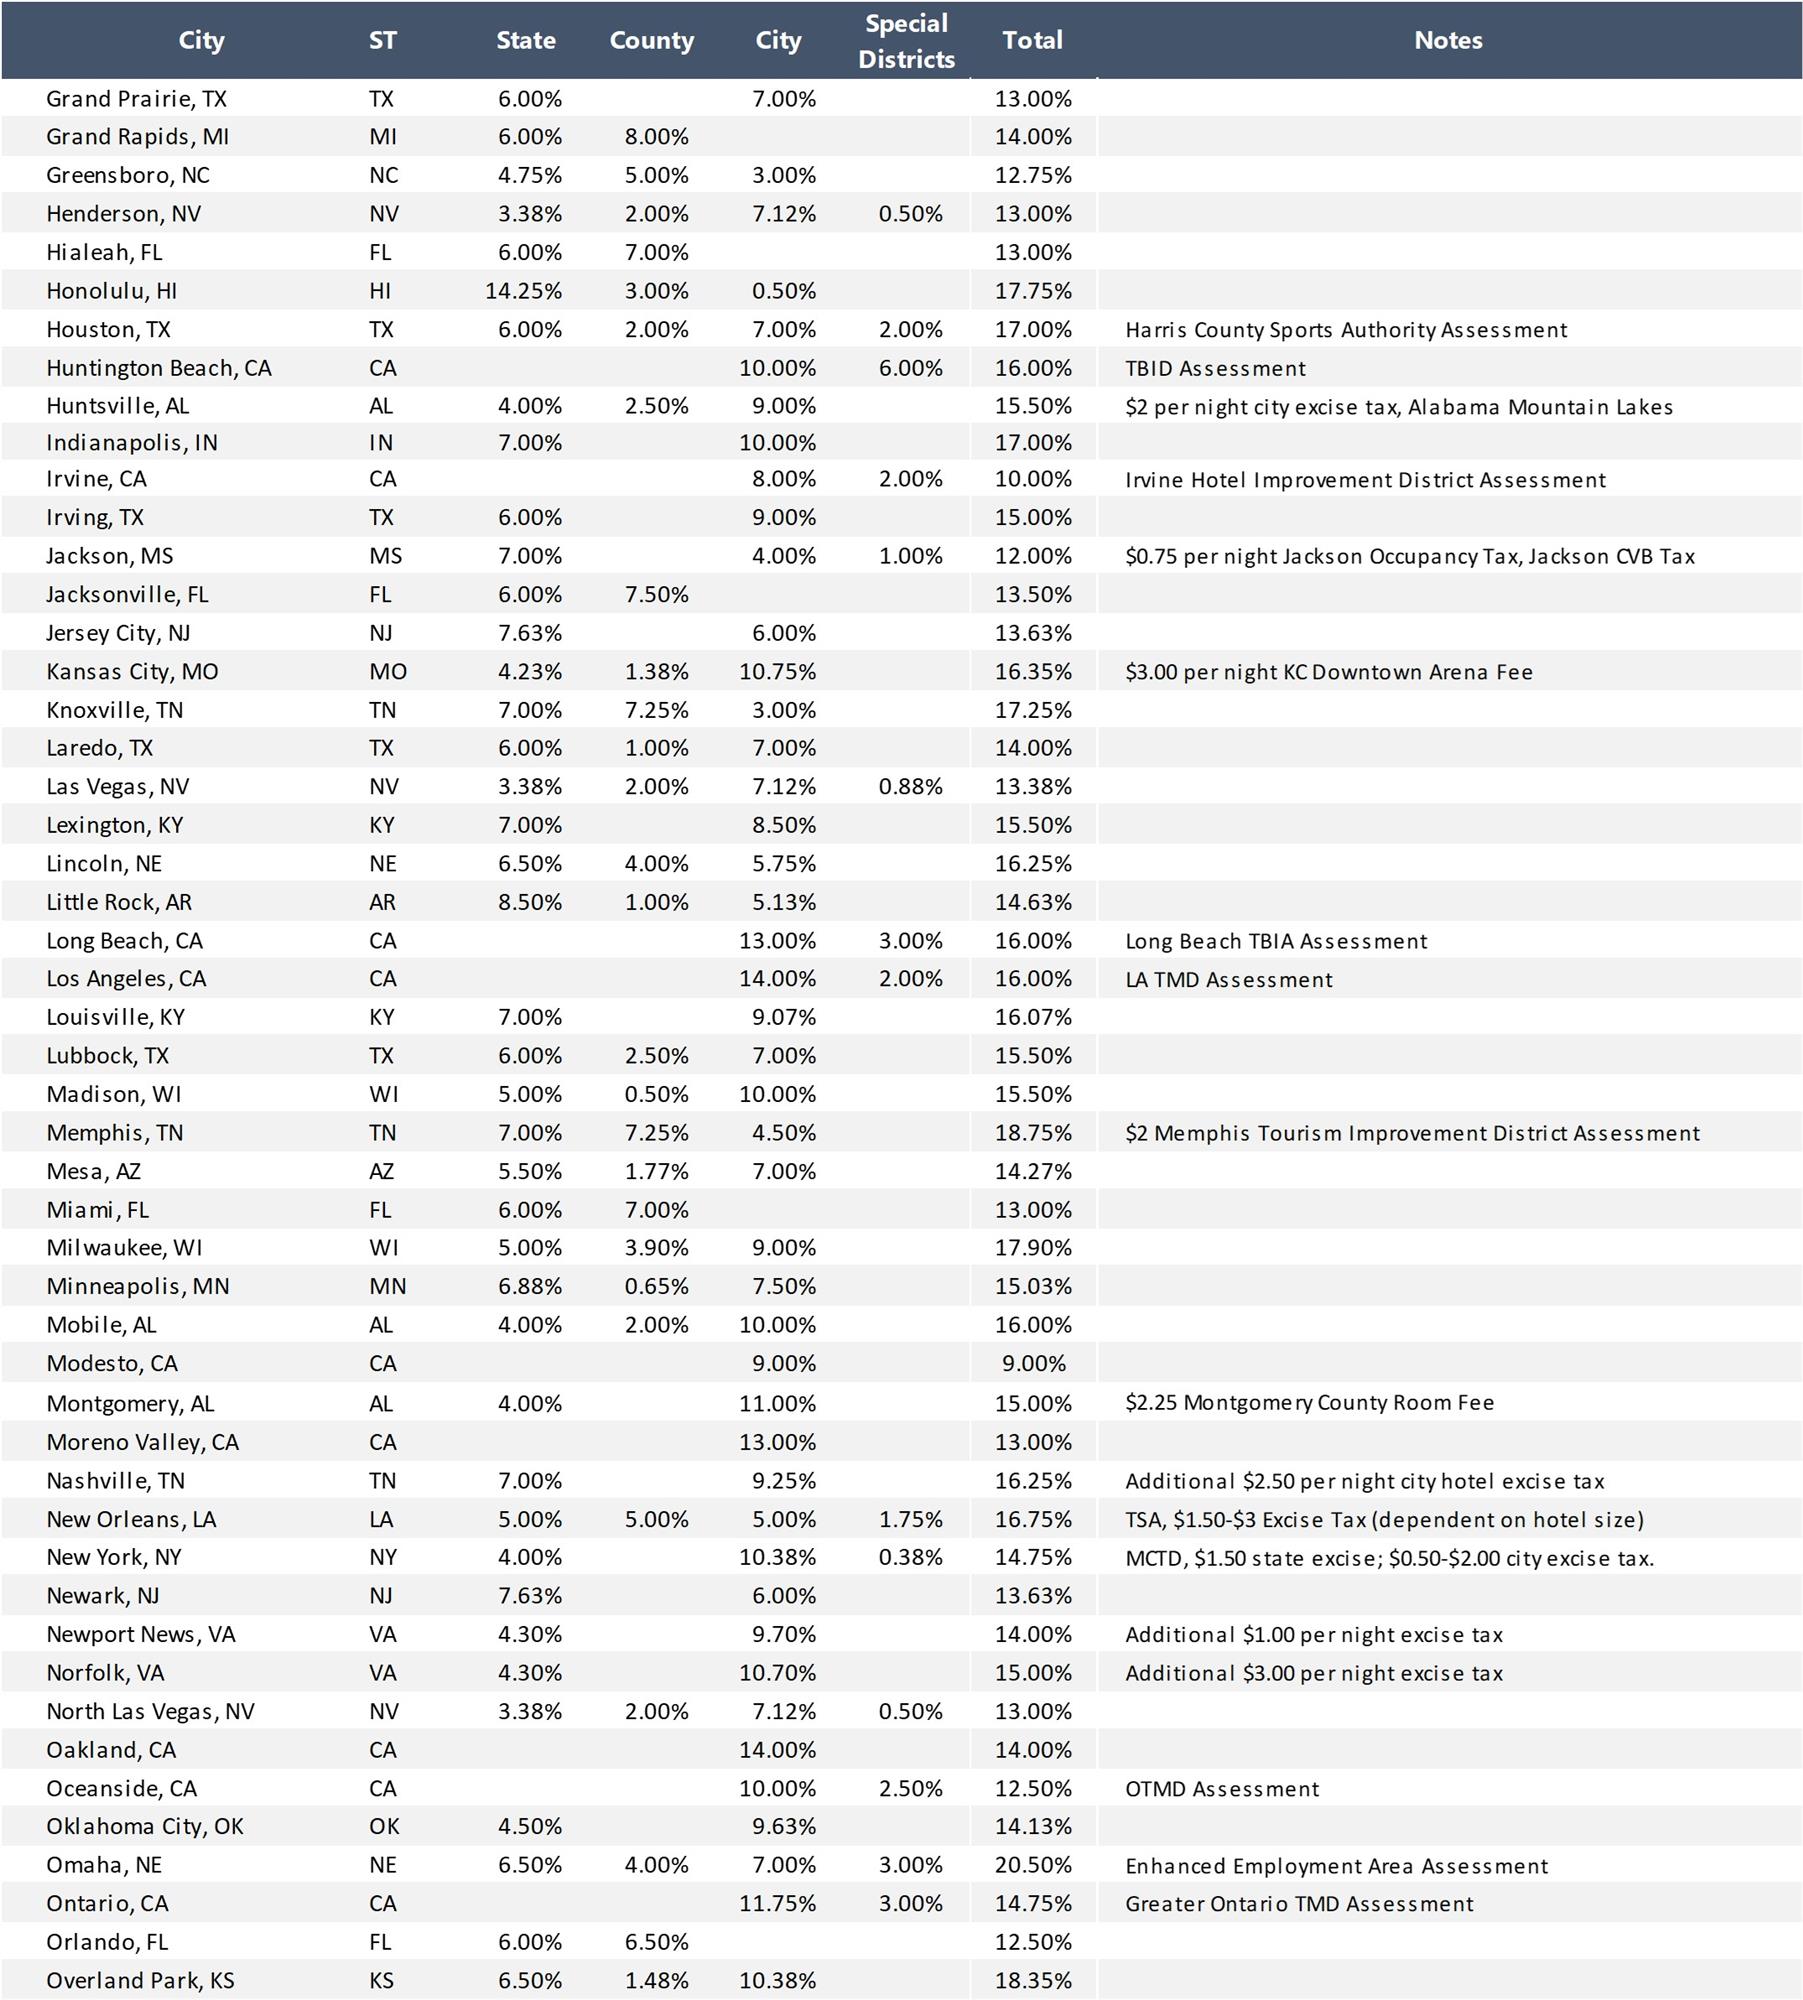
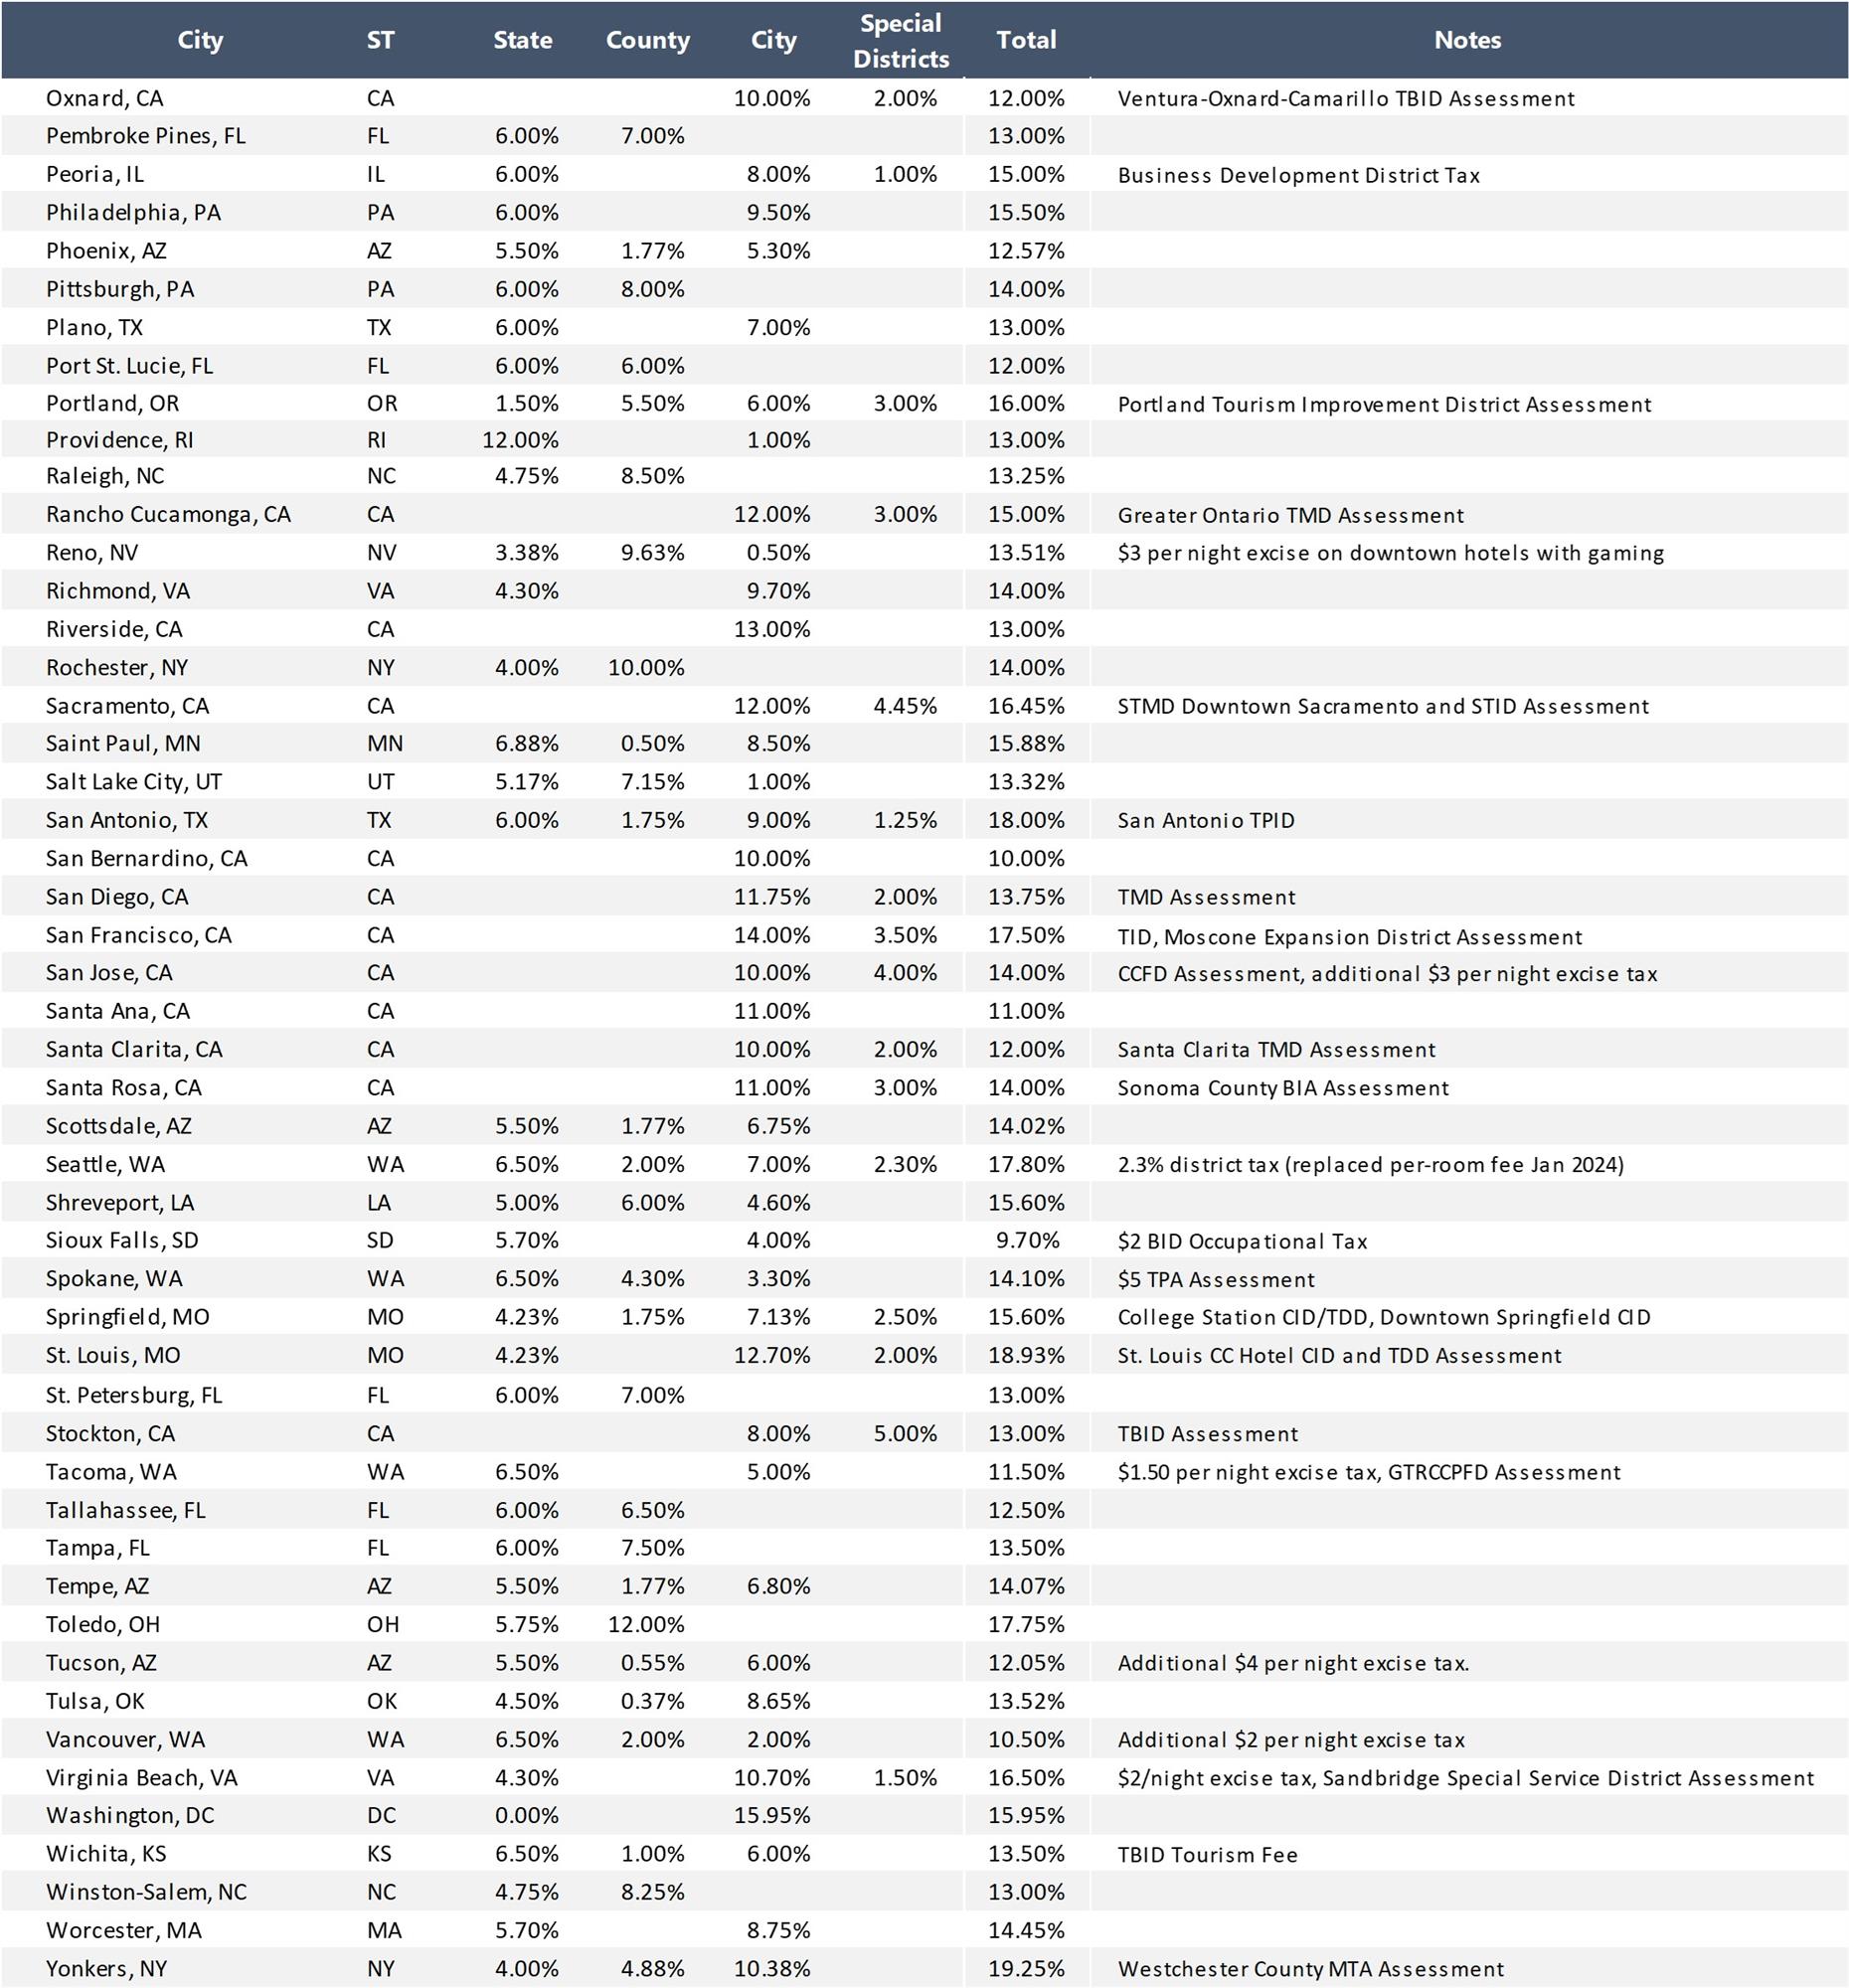
HVS researched the total tax rate applied to lodging accommodations in the 150 most populous US cities as projected from the 2010 census. The total tax rate comprises all state, county, city, and special district taxes levied on lodging facilities within the city's urban center, where the highest special district taxes may be applied. The following tables list the tax rate applied to overnight stays at lodging facilities at the state, county, city, and special district levels, as well as the total rate imposed on an overnight stay at a lodging facility in the urban center of each of the 150 largest cities in the United States.
 
Source: Respective Jurisdictions

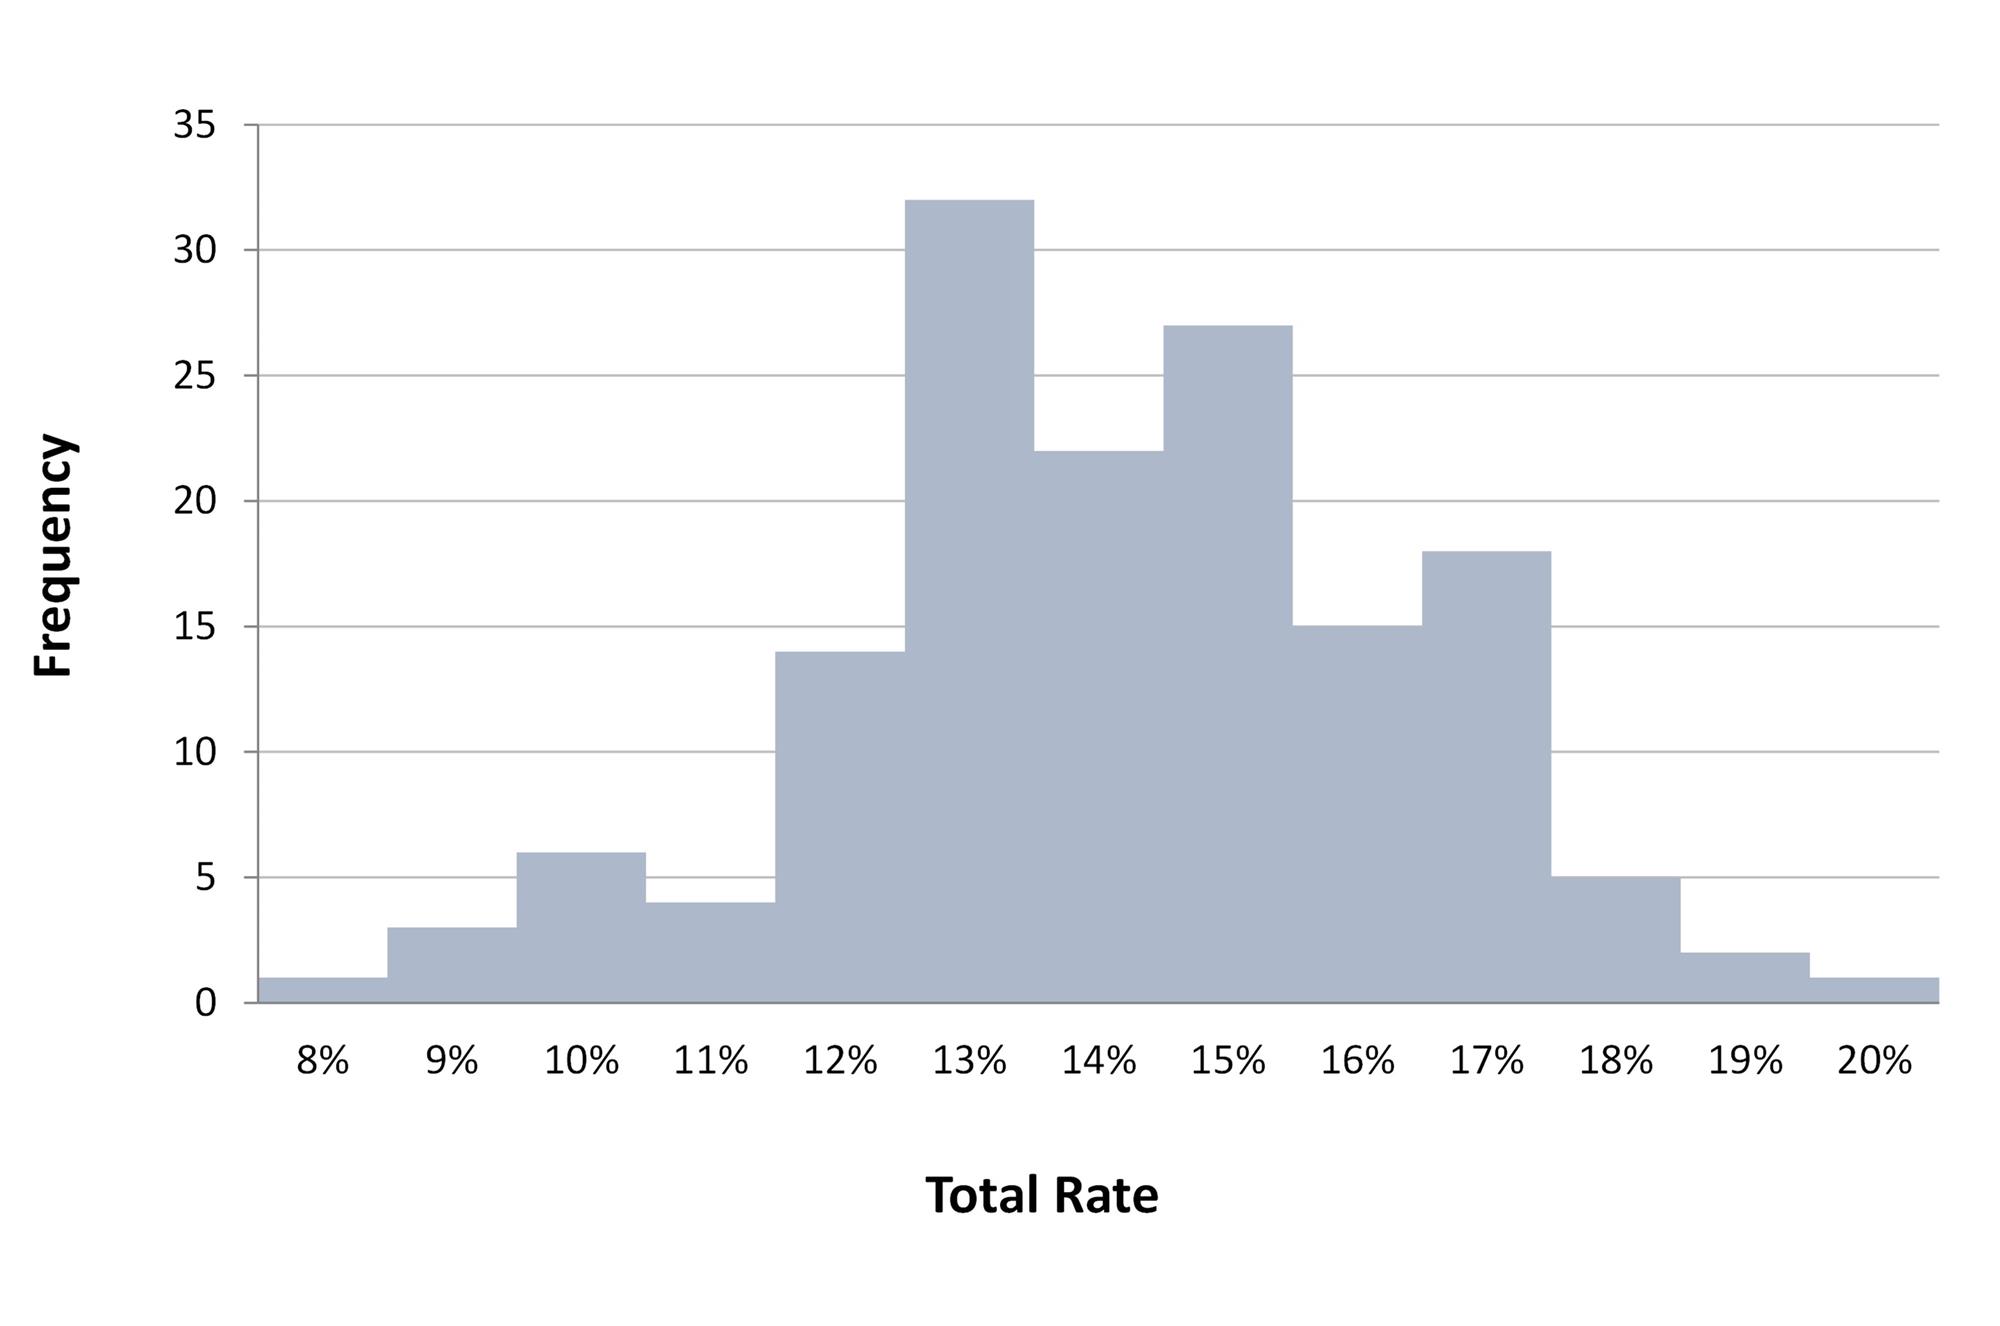
To calculate the special district rate, HVS calculated the tax rate an overnight visitor would pay to stay at the hotel with the highest tax rate within a special taxing district. Due to special taxing districts, the tax rate at a particular hotel can be influenced by its location, size, or other factors that determine tax rates. The figure below shows a distribution of combined lodging tax rates in the 150 largest U.S. cities.

Frequency of Total Lodging Tax Rates
Source: HVS and Respective Jurisdictions

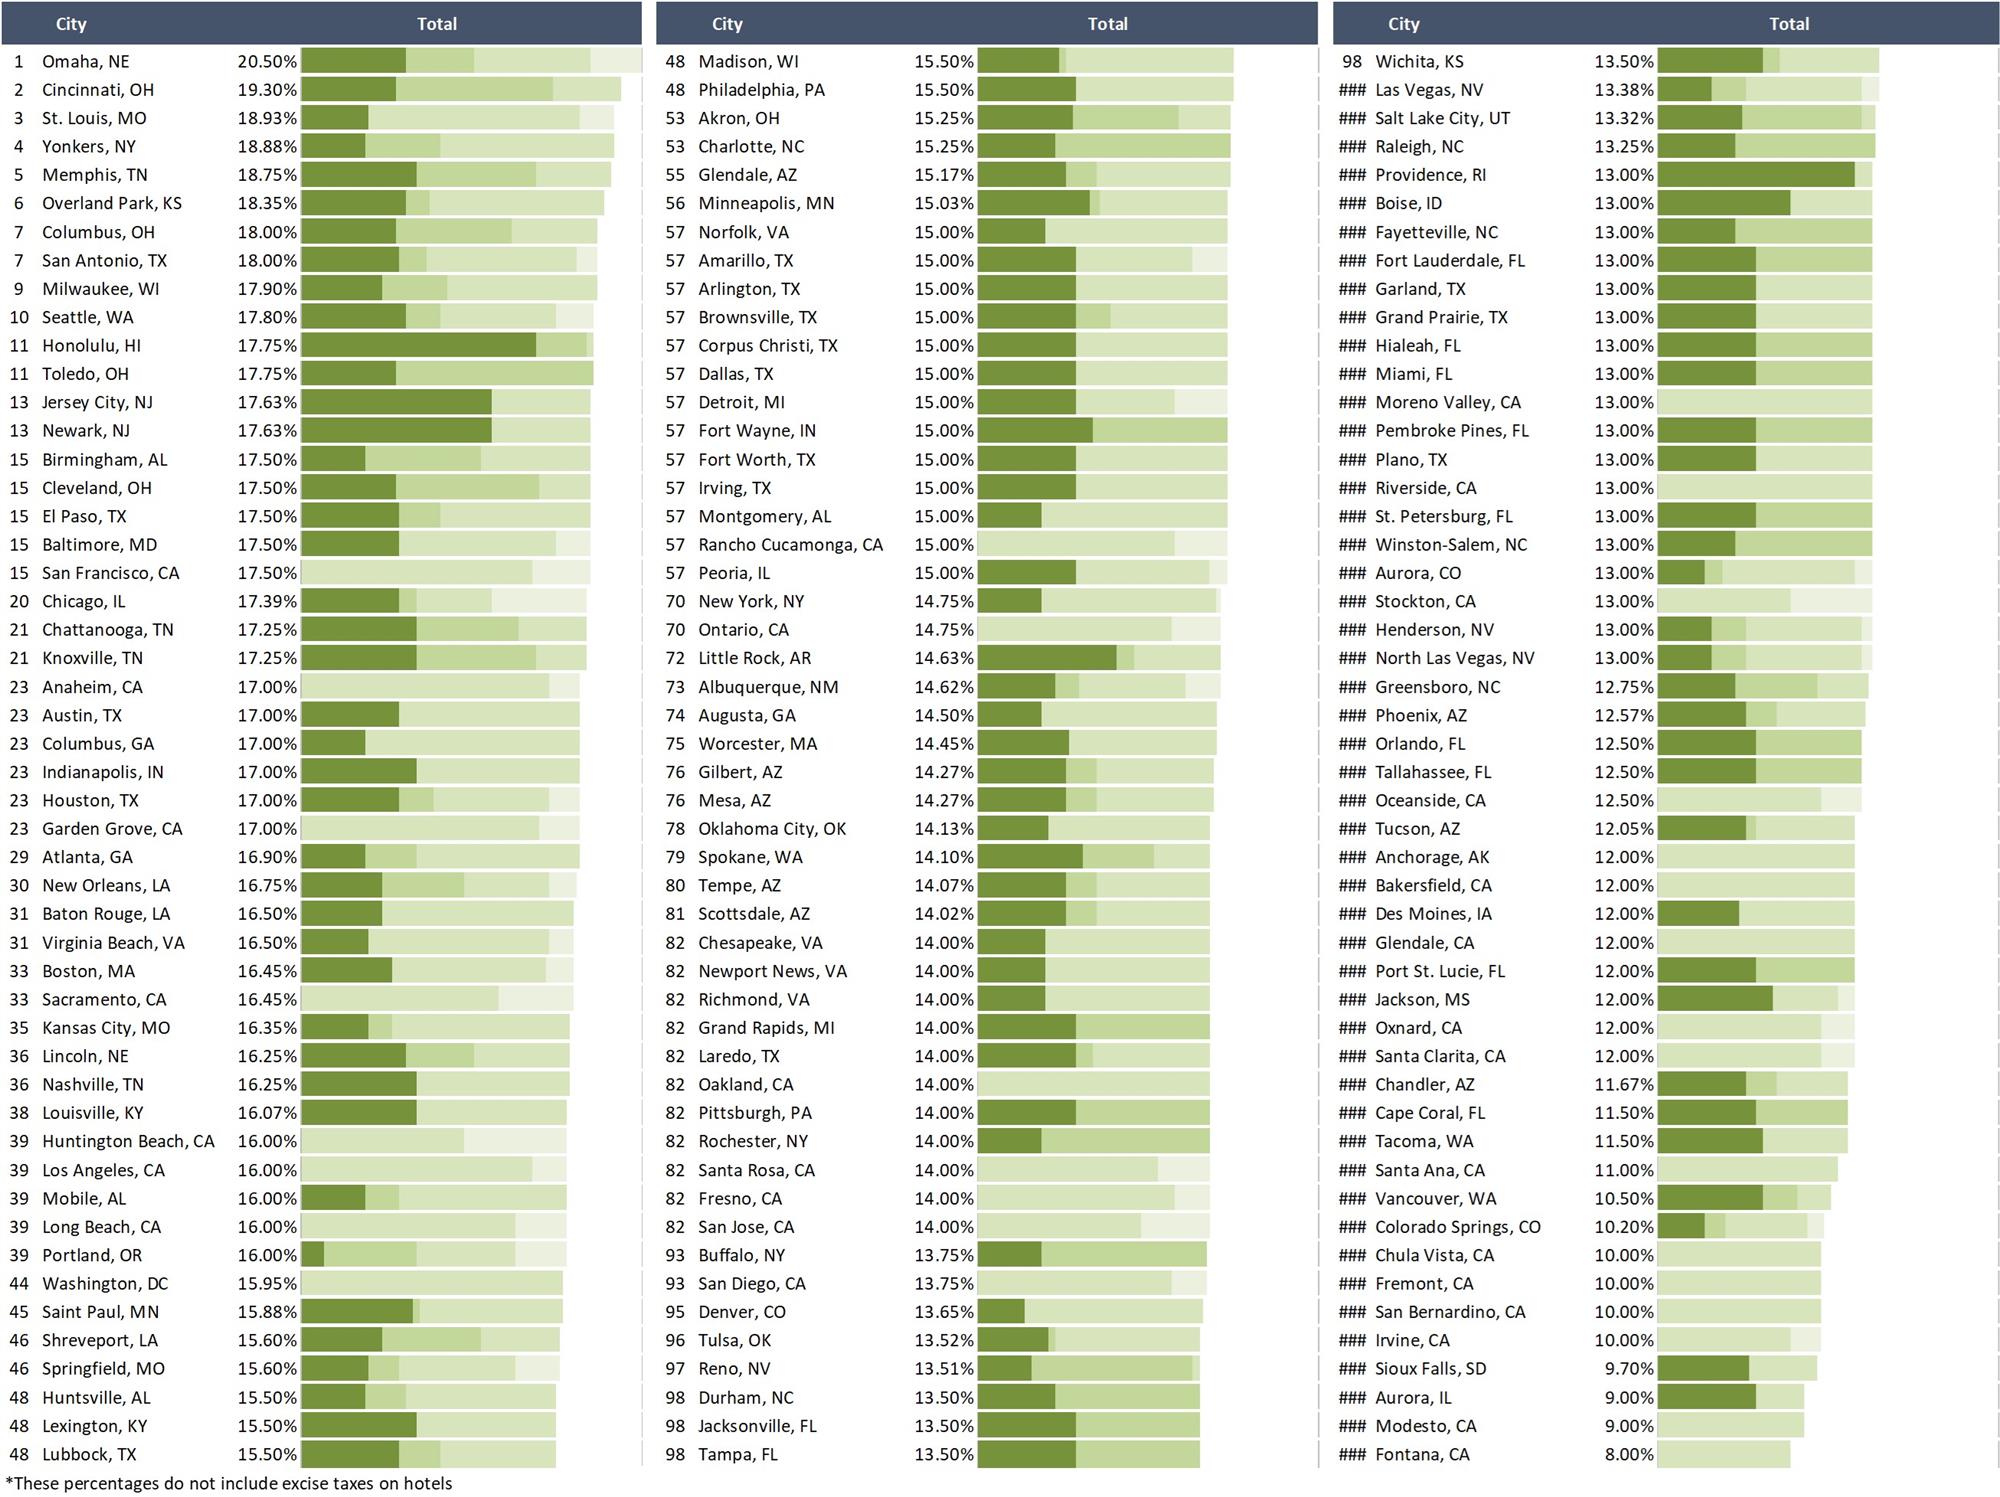
The following table ranks 150 cities by total lodging tax rate. If state or local general sales taxes apply to lodging sales, this rate includes the total tax rate. This analysis enables a comparison of cities’ total tax rate. The figure below provides a breakdown of tax rates by government unit.
 
Top 150 Urban Centers Total Lodging Tax Rate Ranking 2025*
Source: Respective Jurisdictions
 
Tax Rates in Top 150 Urban Centers 2025
Source: Respective Jurisdictions
 
Tax Rates in Top 150 Urban Centers 2025 - Continued
Source: Respective Jurisdictions
 
Tax Rates in Top 150 Urban Centers 2025 - Continued
Source: Respective Jurisdictions

City Lodging Tax Revenue

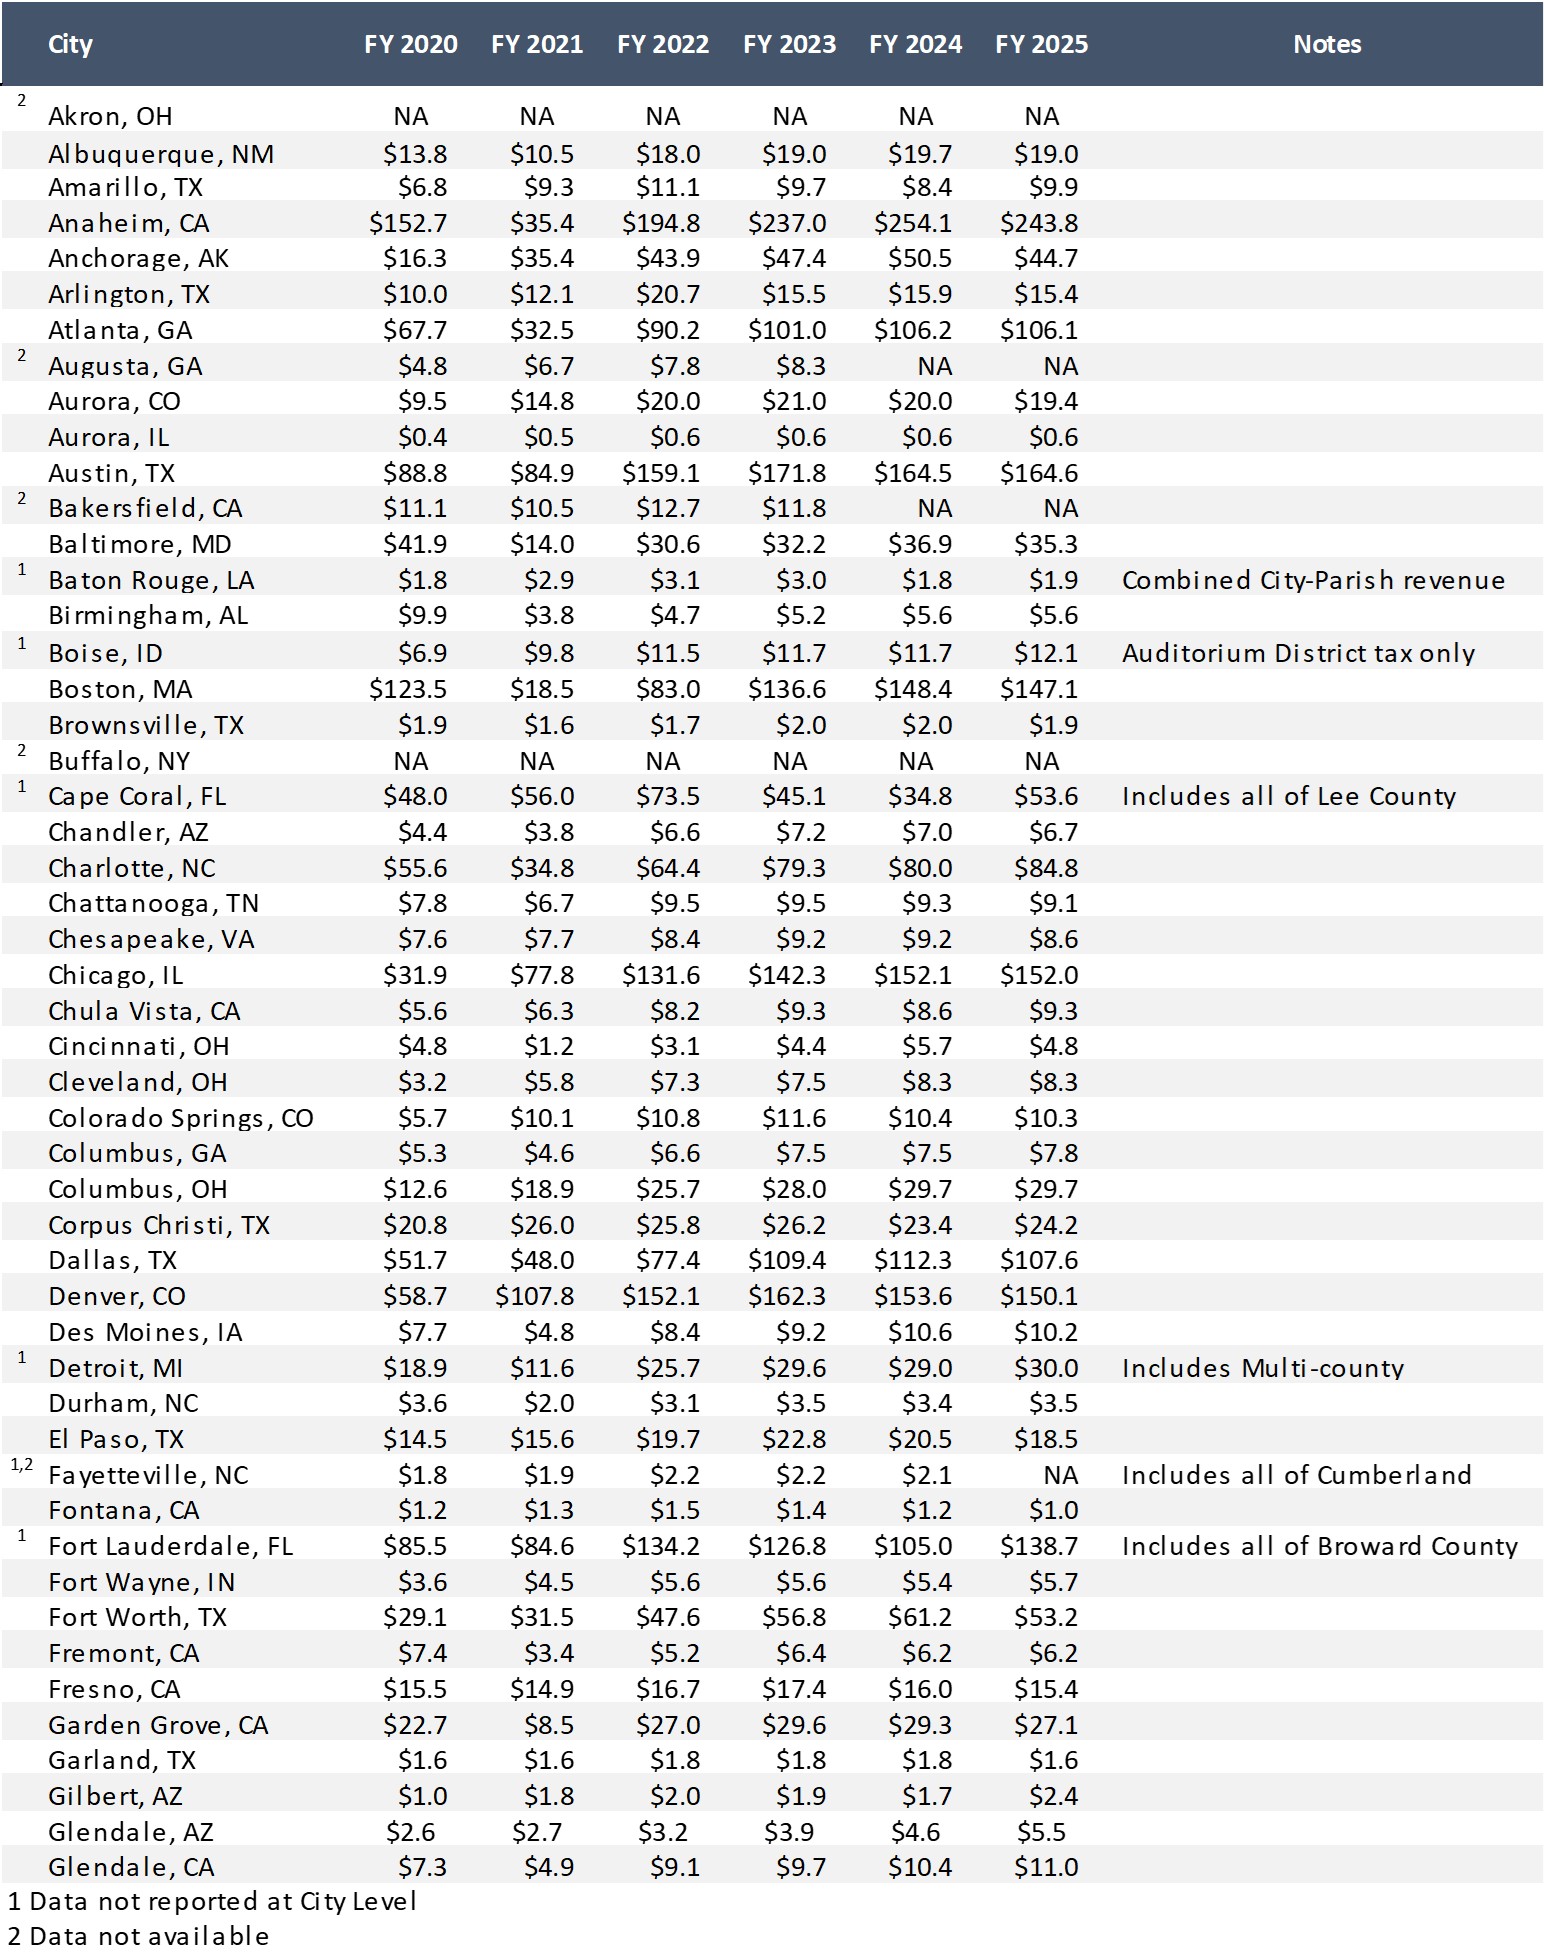
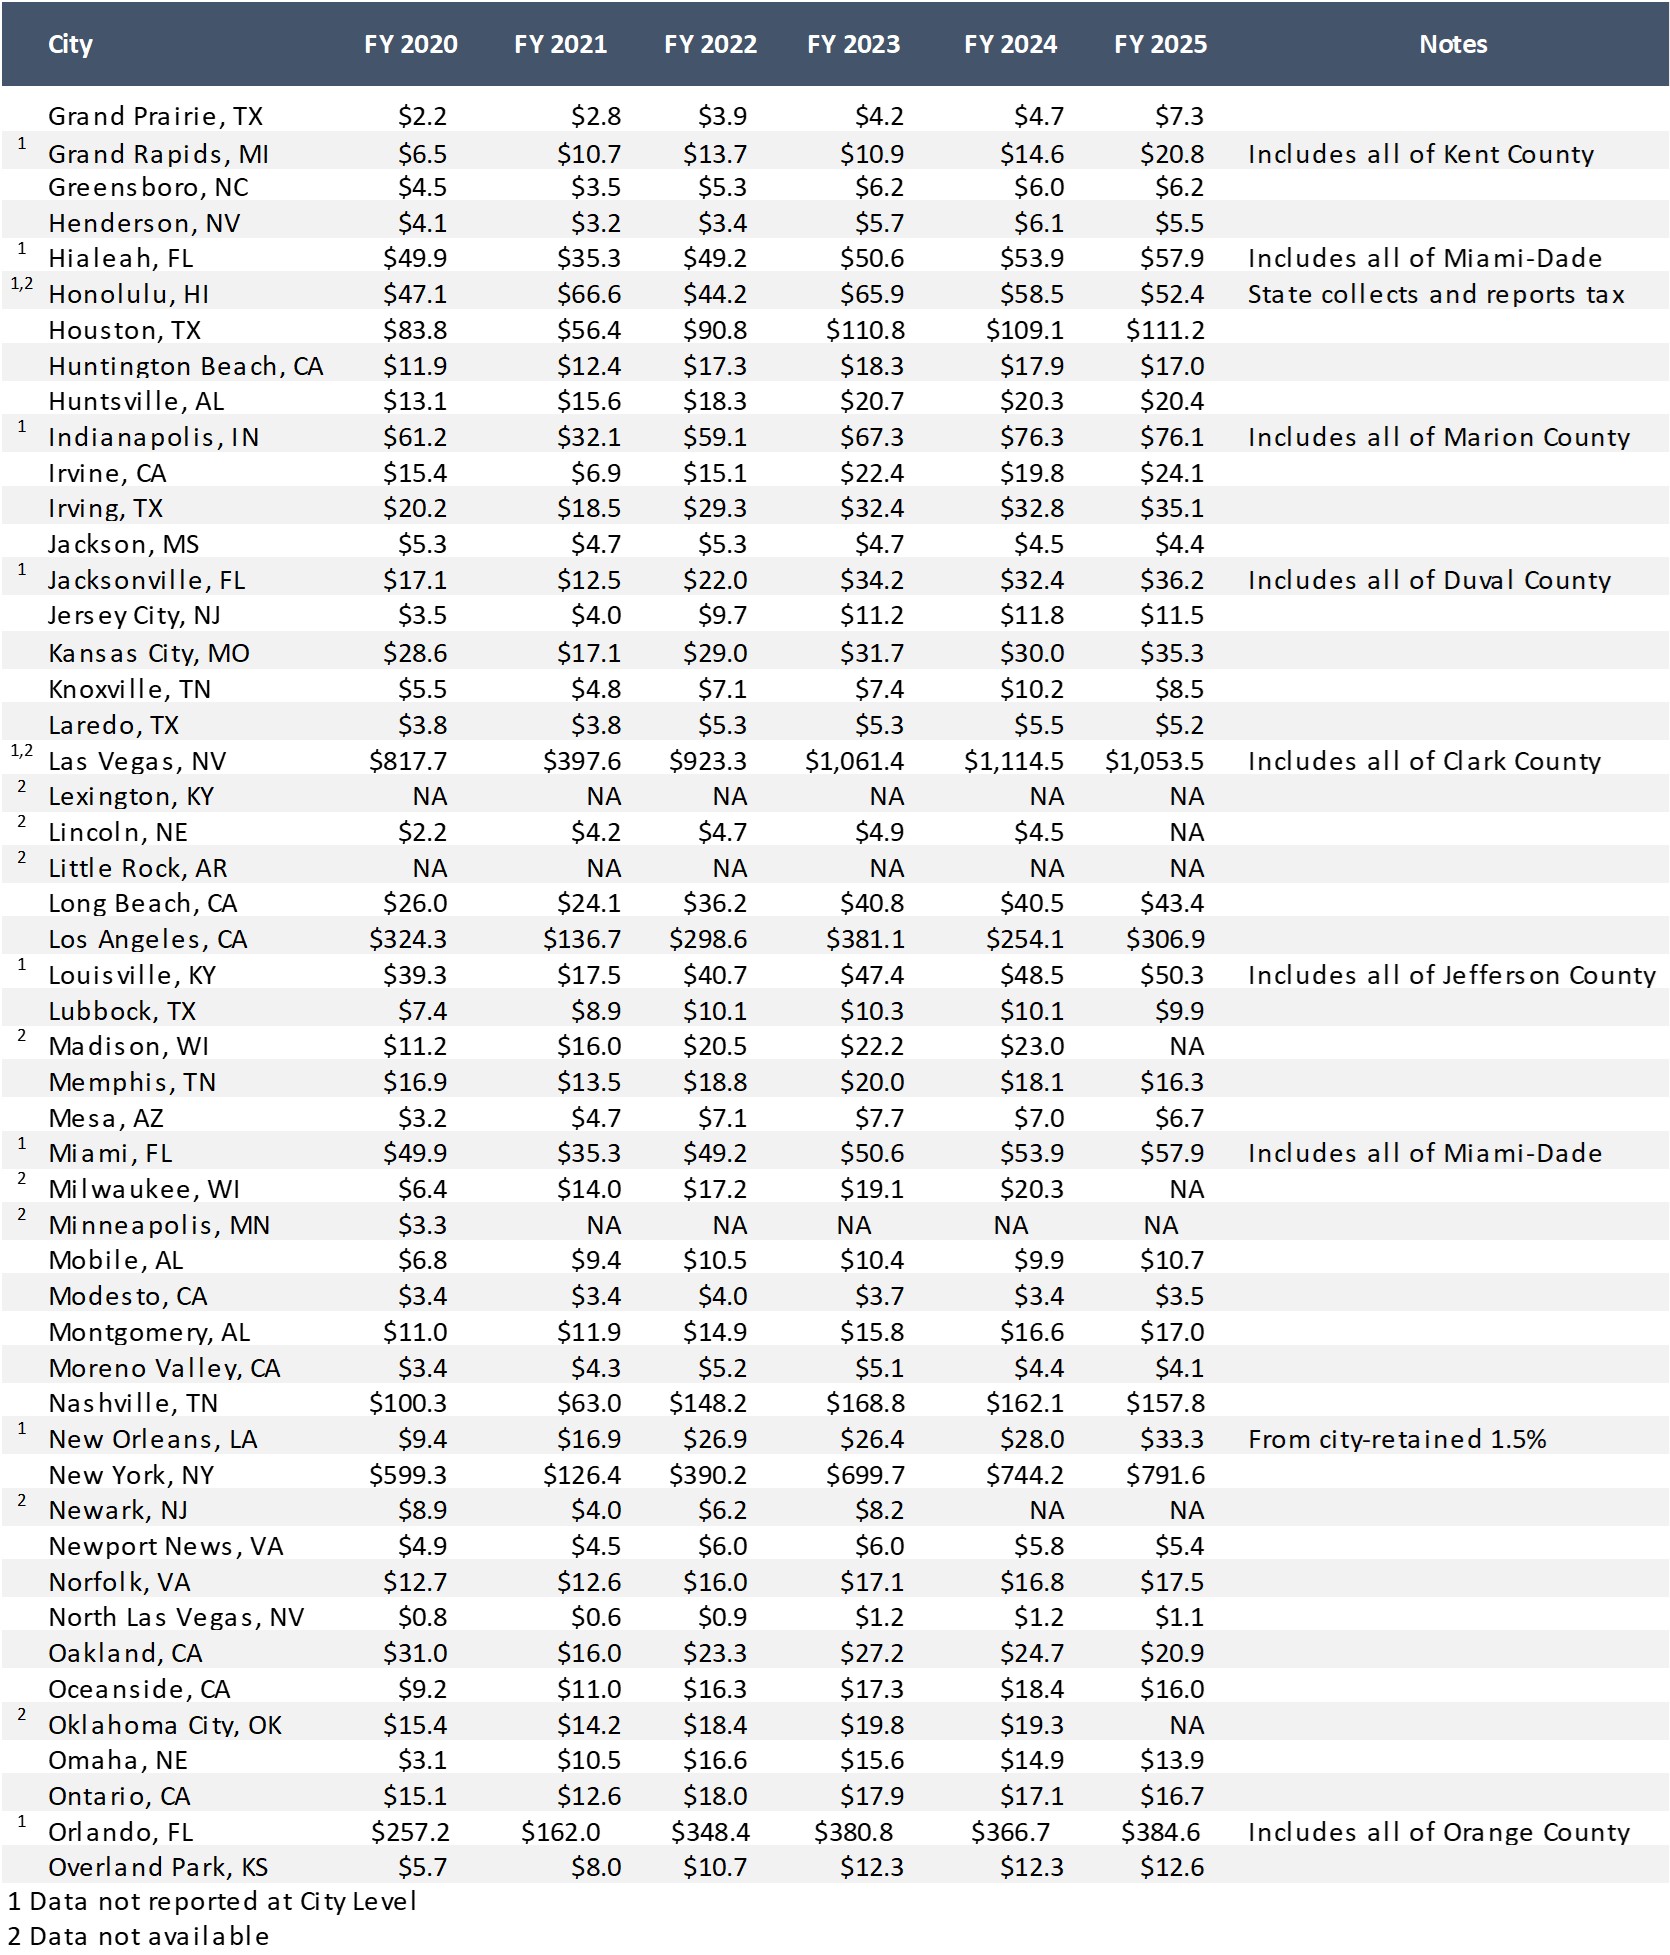
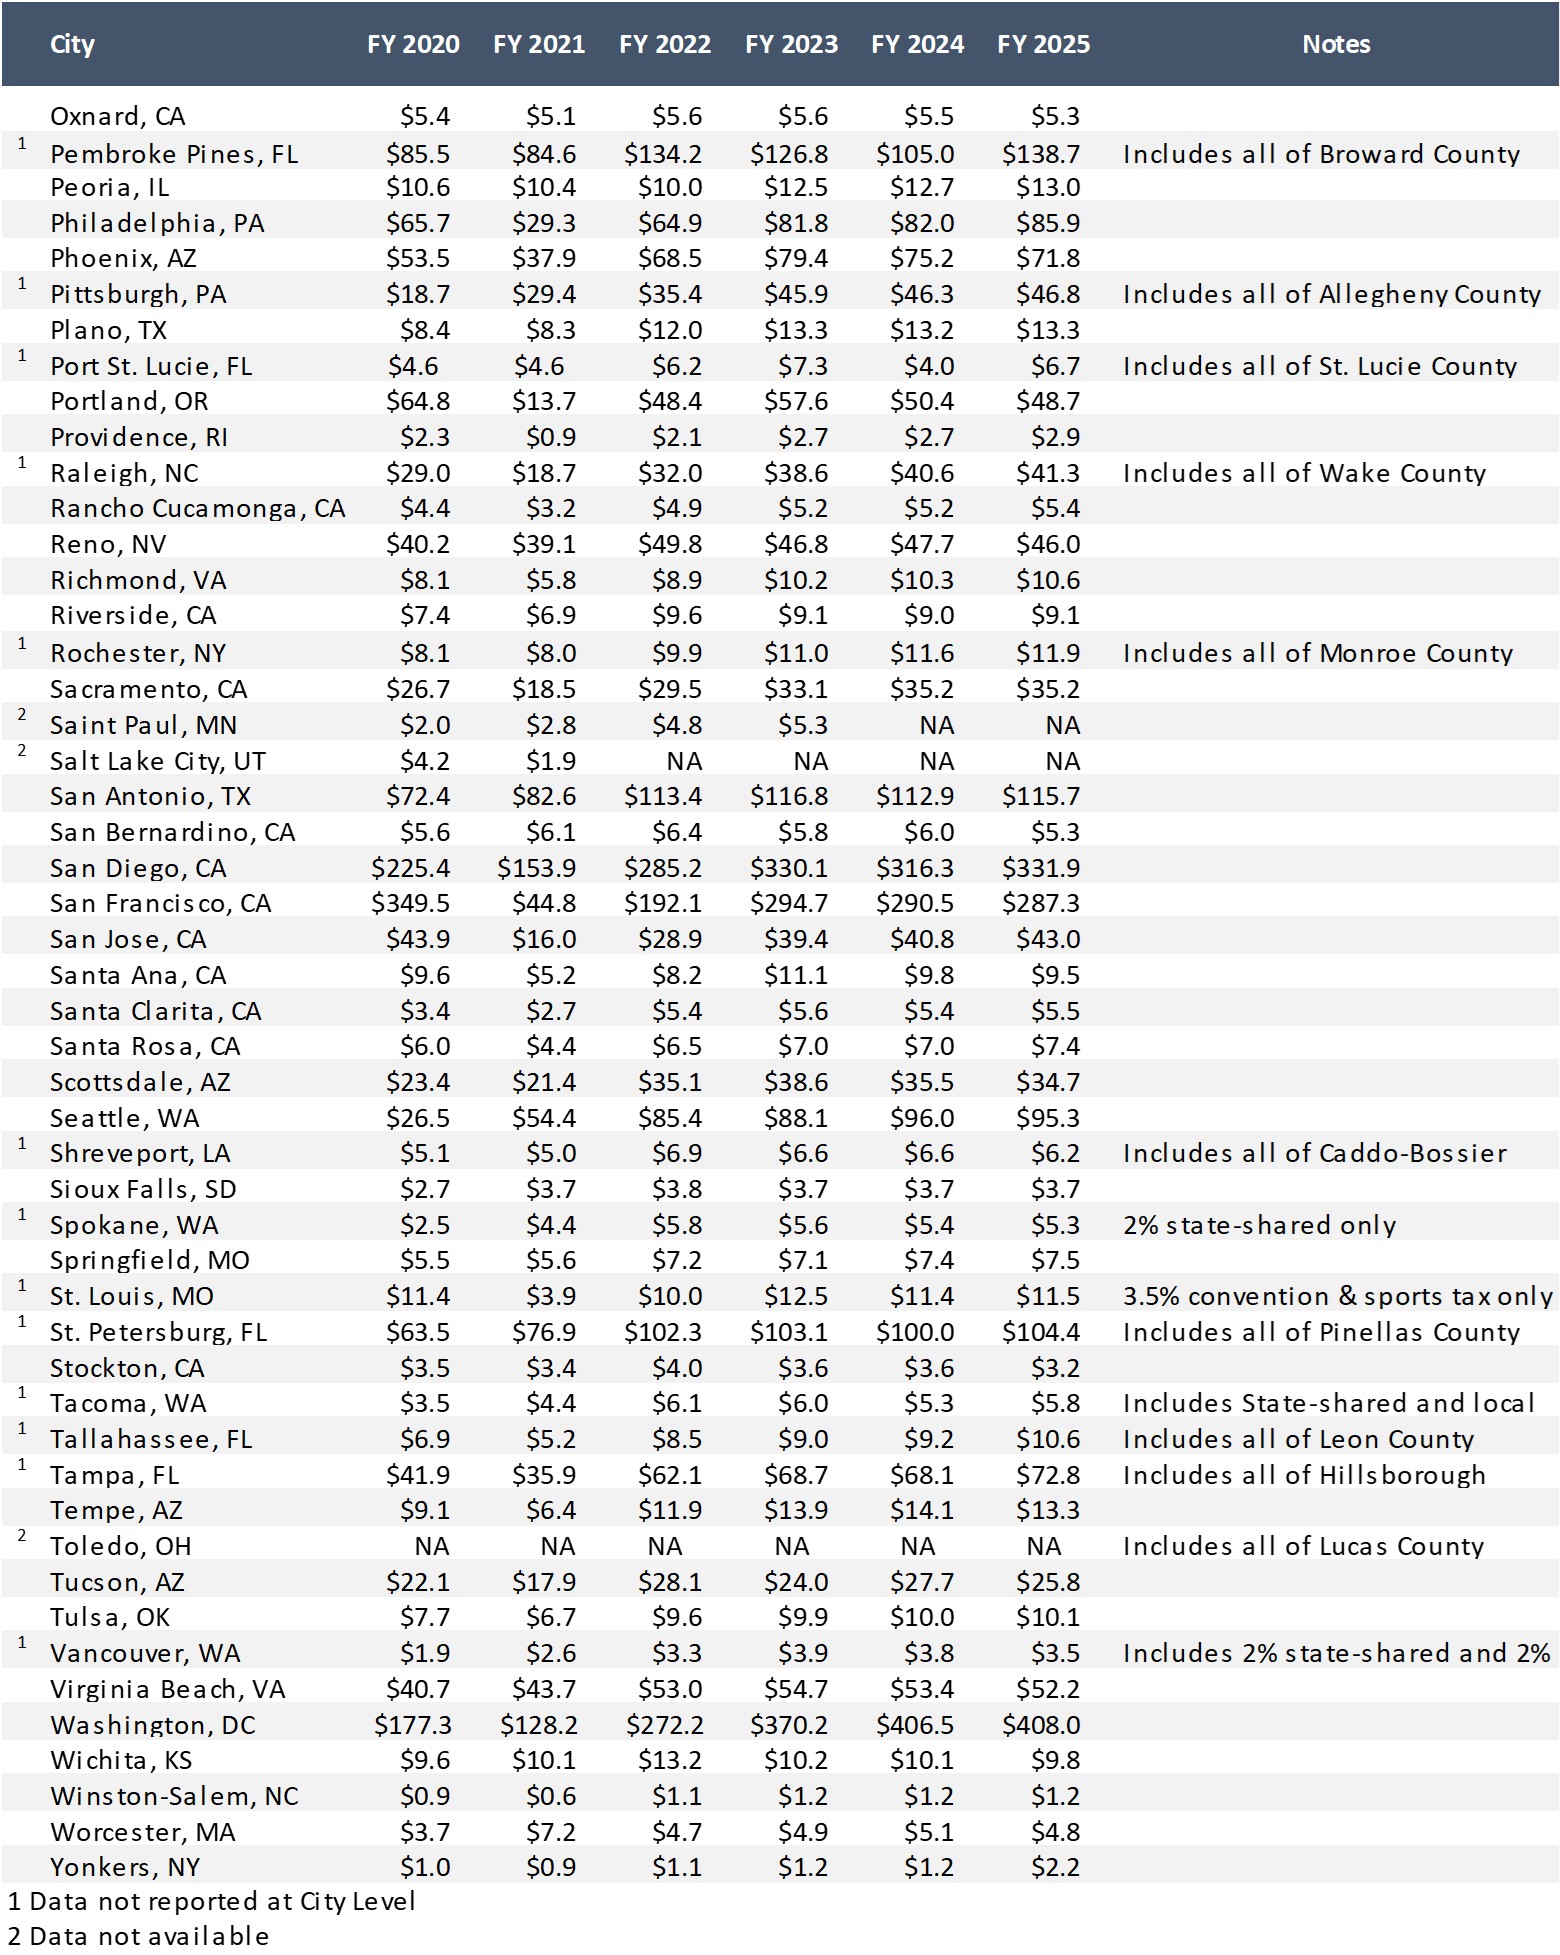
The following tables describe the lodging tax revenue that the 150 most populous cities collected from lodging taxes. Unless otherwise noted, the tax rate and revenue listed only pertains to the citywide lodging tax and excludes special district or city sales taxes. Unlike most lodging tax revenues, sales tax revenues typically flow to general government funds and are not separately reported for the lodging sector.

Consequently, the revenue figures presented for comparable cities can diverge greatly. For example, a city in California with an average lodging tax rate will show greater revenue year over year than a similar city in Nevada, where taxes are levied primarily at the state and special district level. For individual cities, revenues are reported from consistent sources each year.

In some states and cities, lodging taxes are imposed by the county rather than city level. For example, cities in Florida, Indiana, and parts of New York do not levy municipal lodging taxes. In such cases, we list county lodging tax revenues. Year-over-year revenue changes may reflect tax rate changes and underlying changes in taxable receipts for lodging.
 
Reported Lodging Tax Revenues in Top 150 Urban Centers ($ Millions)
Source: Respective Jurisdictions
 
Reported Lodging Tax Revenues in Top 150 Urban Centers ($ Millions) - Continued
Source: Respective Jurisdictions
 
Reported Lodging Tax Revenues in Top 150 Urban Centers ($ Millions) - Continued
Source: Respective Jurisdictions

Excise Taxes

In addition to percentage taxes on gross room revenues, some hotels are subject to excise taxes on lodging transactions and may be charged a flat fee per room night. Excise taxes tend to be less volatile because they only depend on occupancy and are not subject to room price variations. However, excise taxes do not grow with inflation or room rate increases.

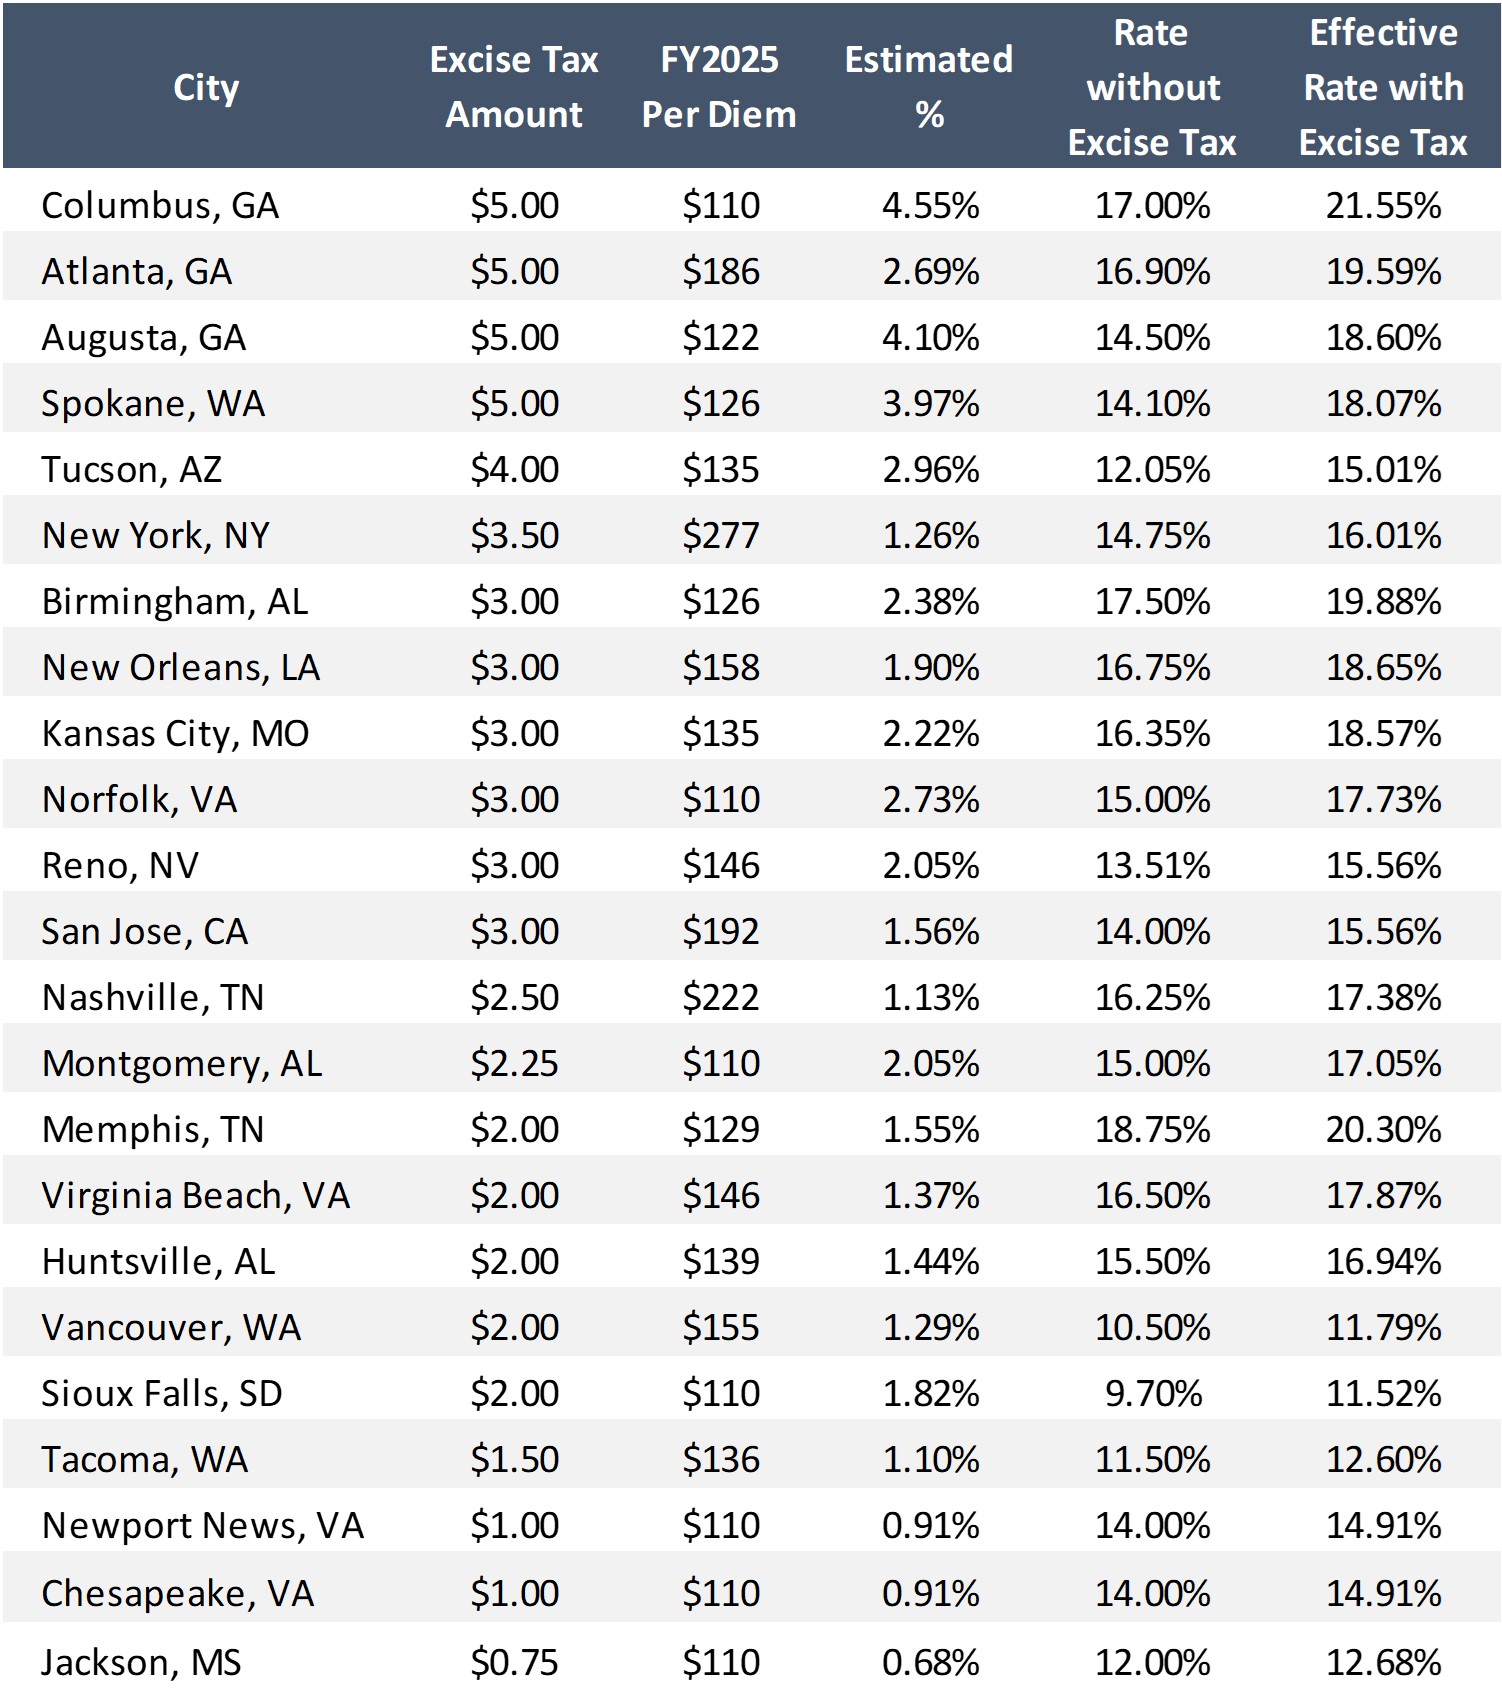
Hotels in 23 cities are subject to a state, city-wide, or special district excise tax. Excise taxes range from $0.75 to $5.00 per room night, with an average of $2.80. HVS calculated each city’s excise tax as a percentage of its per diem rate (in fiscal year 2025 dollars) to estimate effective tax rates. A city’s effective rate indicates the average rate a person pays if the excise tax were included as a percentage of the total sale price. For this example, HVS used the per diem rates set by the General Services Administration (GSA). The per diem rates set by the GSA are usually lower than the average daily rates at hotels in the specified areas. The chart below is for illustrative purposes only.

On average, every dollar charged in excise tax is roughly equivalent to an ad valorem tax increase of 2.03% for 2025.

Selected Effective Rates of Excise Taxes
Source: HVS, GSA, and Respective Jurisdictions

Airbnb Lodging Tax Collections

Short-term home rental services such as Airbnb and VRBO have grown even more popular among travelers, with Airbnb being the dominant player in the market. 2025 marked another record year for Airbnb, with total revenue of $12.2 billion, a 10% increase from 2024, which had previously set a record. Growth was driven in part by an 8% increase in nights and experiences booked, which reached 533 million. Listings in North America accounted for 42% of 2025's revenue, down from 45% in 2024, as growth in Europe and Latin America outpaced North America. Often referred to as part of the sharing economy, these peer-to-peer platforms enable homeowners or hosts to rent out a spare room, an entire house, or an apartment to travelers seeking unique travel experiences and accommodations. Airbnb has experienced exponential growth since its founding. In 2025, Airbnb's adjusted EBITDA reached $4.3 billion, up from $4.0 billion in 2024, reflecting continued strong business performance.

In response to Airbnb's growth, cities have been compelled to address challenges stemming from the impact of short-term rentals. Residents have raised concerns over the neighborhood impacts of transient visitation. In response, many cities and states have imposed new taxes and regulations on short-term rentals.

To gain legitimacy and permanence within the United States, Airbnb has urged local governments to permit it to collect and remit lodging taxes on behalf of its hosts. In recent years, states and cities have made considerable efforts to collect taxes from Airbnb. Since January 1, 2025, Delaware has imposed a 4.5% short-term rental lodging tax on all short-term rentals, including those listed on platforms such as Airbnb. Hawaii remains the only U.S. state in which Airbnb does not collect and remit taxes on behalf of the state.

Click here to download the full 2026 HVS Lodging Tax Report.

Disclaimer

HVS’s lodging tax study recognizes that lodging tax rates, collections, and distributions are in constant flux. The data presented herein are HVS’s best attempt to gather the most recently available information. HVS used sources deemed to be reliable and assumes that this information is accurate. All questions, comments, or concerns are welcome in the continuing process to accurately present the current and historical trends of lodging taxes in the United States. 

[1] HVS, "How the 2026 FIFA World Cup Changed US Hotel Markets," Retrieved August 6, 2026.

[2] US Congressional Research Service, "Supreme Court Rules Against Tariffs Imposed Under the International Emergency Economic Powers Act (IEEPA)” Congressional Research Service," Retrieved October 8, 2026.

[3] Oxford Economics, "Oxford Economics," Retrieved October 8, 2026.

[4] Typically defined in ordinances as being fewer than thirty days.

[5] Home rule cities are cities that have their own taxing authority, have adopted home rule charter for their self-governance, and are not limited to exercising only those powers that the state expressly grants to them.

Market Report

2026 HVS Lodging Tax Report - USA

October 26, 2026
This 16th annual Lodging Tax Study presents data on city, state, and special district lodging and sales taxes imposed on lodging sales. We provide historical data on tax rates and collection and distribution of revenue from lodging taxes levied in all 50 States and the 150 largest US cities. Our analysis of 25 major U.S. hotel markets shows more markets declining than growing in 2025. Through August 2026, RevPAR rose in all but one market, signaling broad-based improvement in hotel performance.

Source: iStock.com/Evgeny Kuklev

Lodging Industry Overview

Since room sales generate lodging tax revenues, an overview of hotel market trends provides insight into the industry’s current and future fiscal impacts. As documented in our 2025 HVS Lodging Tax Study, the national lodging market has experienced recent growth in average daily room rates and revenue per available room. However, occupancy levels have remained relatively flat. The Average Daily Room Rate (“ADR”) represents the average revenue earned for each room rented in a hotel. Revenue per available room (“RevPAR”), the product of ADR and occupancy rate, is a standard industry metric that combines the effects of occupancy and room rates on overall revenue performance. ADR and RevPAR increased in 2024, while RevPAR declined slightly in 2025 as occupancy fell. Through the first eight months of 2026, all three metrics have improved compared to the same period in 2025. The figure below compares year-over-year growth in occupancy, ADR, and RevPAR for the entire U.S. lodging market, based on CoStar data, from 2024 through August 2026.

Year-Over-Year Changes in U.S. Lodging Market Figures From 2024-2026

Source: CoStar
 
Occupancy declined in 2025 compared to 2024, with ADR growth also slowing due to reduced leisure travel and greater consumer price sensitivity, resulting in a slight decline in RevPAR. Year-to-date 2026 data through August shows a rebound, with occupancy up approximately 1.4% and ADR up approximately 3.4%, driving RevPAR growth of nearly 5%. The following figure shows the year-over-year change in room revenue for the top 25 major U.S. markets as measured by city population. We compared 2024, 2025, and year-to-date 2026 rates of change in room revenue.

Top 25 US Lodging Markets: Year-Over-Year Growth of Rooms Revenue

Source: CoStar

Room revenue performance diverged sharply across the top 25 U.S. markets from 2024 to 2025. Ten markets posted gains, Philadelphia was flat, and the remaining 14 markets recorded declines. San Francisco led all markets with a 14.5% increase in room revenue, well ahead of New York City (6.8%), Oklahoma City (6.4%), and Columbus (5.8%). At the other end of the range, Las Vegas (-10.4%), Houston (-8.7%), and El Paso (-7.3%) saw the steepest declines. With more than half of the top 25 markets reporting lower room revenue, these results point to a softening of the revenue base on which lodging taxes are levied, and lodging tax collections in many major markets are likely to flatten or decline in the near term.

Hotel room revenue is the base on which most lodging taxes are levied, so the size of each market's room revenue, along with its tax rate, determines the scale of its lodging tax collections. CoStar reports room revenue net of taxes, so the figures below reflect pre-tax room sales and exclude the lodging taxes collected on them. Short-term rentals also generate lodging taxes in nearly all jurisdictions, but this impact is not captured in the CoStar data.

The following figure shows 2025 room revenue for the top 25 U.S. lodging markets.

Top 25 US Lodging Markets: 2025 Room Revenue
Source: CoStar

The top 25 markets generated approximately $54.0 billion in room revenue in 2025, but that revenue is highly concentrated. New York City and Las Vegas stand well apart from the rest, together accounting for more than 40% of the total, and New York City alone generated more than four times the revenue of Chicago, which ranks third in room revenue. Most of the remaining markets fall within a narrower band of $1 billion to $3 billion, while the nine markets below $1 billion together contribute only about a tenth of the total.

While room revenue reflects the overall size of a market, RevPAR measures how much revenue each available hotel room generates, combining occupancy and average daily rate into a single measure of performance. Comparing RevPAR across markets shows which destinations earn the most from each room, regardless of how many rooms they have. The following figure shows 2025 RevPAR for the top 25 U.S. lodging markets.

Top 25 US Lodging Markets: 2025 RevPAR

Source: CoStar

RevPAR varied widely in 2025, with New York City and Boston leading at more than $200 per available room, about four times the level in Oklahoma City. RevPAR rankings often differ from room revenue rankings. Las Vegas and Houston rank among the top ten in room revenue but lower in RevPAR, reflecting the scale of their markets rather than performance per room. Boston shows the opposite, ranking second in RevPAR but seventh in room revenue. These differences show that high-performing markets such as Boston generate strong lodging tax collections from each room, while high-volume markets such as Las Vegas and Houston produce large collections through the sheer size of their hotel markets.

While the previous figures reflect full-year 2025 performance, 2026 year-to-date data provides an indication of where the lodging tax base is heading. The following figure shows the year-to-date percent change in RevPAR for the top 25 U.S. lodging markets in 2026 compared with 2025.

Top 25 US Lodging Markets: 2026 RevPAR Outlook

Source: CoStar
 
Hotel performance has strengthened broadly in the first eight months of 2026. Combined year-to-date room revenue across the 25 markets rose 7.8% compared with the same period in 2025, to approximately $37.3 billion, and RevPAR increased in all but one market. San Francisco and San Jose led with gains of 21.5% and 18.0%, lifted by AI and technology conventions, along with Super Bowl LX and the FIFA World Cup in Santa Clara. Austin was the only market to decline, largely due to the closure of its convention center for redevelopment, which removed the hotel demand generated by citywide conventions. New York City and Las Vegas, the two largest revenue markets, experienced more moderate growth. Overall, broad-based RevPAR growth points to a recovering lodging tax base after a softer 2025, although modest gains in several large markets may slow the recovery in total collections.

Many of these markets hosted 2026 FIFA World Cup matches, which likely contributed to the widespread RevPAR growth through August 2026.[1] The following figure shows the estimated rooms revenue impact in each U.S. host market.
 
Rooms Revenue Changes during FIFA Match Weeks

Source: CoStar data and HVS Analysis

The 2026 FIFA World Cup generated a substantial impact on hotel performance across its eleven U.S. host markets, producing an estimated $680 million in incremental rooms revenue overall. New York captured by far the largest share at $339.2 million, or $42.4 million per match. On a per-match basis, Boston ranked second at $9.9 million, slightly ahead of Los Angeles. Kansas City's performance was also notable relative to its market size, out-earning larger markets such as Houston and San Francisco on both a total and per-match basis. Because no event of comparable scale is scheduled for 2027, these markets will be measured against an elevated 2026 base. As a result, growth in lodging tax collections may fall below historical trends in 2027.

Economic Uncertainty

This report was prepared during a period of significant uncertainty, marked by multiple changes in U.S. policies that have impacted both the domestic and global economies. Any subsequent change to these perspectives or information could affect the future growth of lodging tax revenues.

Throughout 2025 and into 2026, shifting trade policy and litigation over the legality of the administration's tariffs created widespread uncertainty surrounding how the U.S. and global economies may respond.[2] Since late February 2026, the conflict with Iran has pushed energy prices higher, adding to inflationary pressure and prompting the Federal Reserve to raise interest rates. Areas of concern include rising energy and borrowing costs, which, combined with inflation, would further increase the cost of doing business and continue to impact the pipeline for new development. Tighter household budgets could also affect domestic travel, including both transient and group activity. In addition, the U.S. government’s immigration and visa policies may result in a shortage of hospitality workers.

Geopolitical concerns have influenced global travel to the US. Tourism Economics estimates that international overnight visits to the U.S. fell 5.7% in 2025, driven largely by a 25.7% decline in visits from Canada, and expects ongoing policy uncertainty to limit the recovery in 2026.[3]

Until more clarity emerges, the near-term outlook remains uncertain due to the factors mentioned above. Persistent inflation, higher interest rates, and weakening consumer confidence remain key concerns. Over the long term, the hospitality industry has proven to be extraordinarily resilient following past “shock” events and downturns such as 9/11, the Great Recession, and the COVID-19 pandemic. Despite temporary declines, the industry’s performance has consistently recovered and continued to grow. Thus, we are confident the industry will prove to be similarly resilient following the current period of uncertainty.

Labor Force

Since 2023, employment in the hospitality and leisure sector has grown modestly before leveling off in mid-2025, continuing to support the industry's capacity to meet lodging demand. The graph below compares the number of employees in hospitality with the unemployment rate.

Hospitality and Leisure Sector Employment (Total US)

Source: Bureau of Labor Statistics

After growing from 2023 through mid-2025, employment in the hospitality and leisure sector has remained largely flat at approximately 17.0 million since mid-2025. Unemployment in the sector has remained between 5% and 7.5% since January 2025. A stable workforce allows hotels to meet current demand, though limited employment growth may constrain the industry's capacity to expand as lodging demand, and the lodging tax base, recovers in 2026.

Imposition of Lodging Taxes

Lodging taxes are typically ad valorem taxes (levied as a percentage of value) on short-term[4] overnight stays at hotels, motels, bed-and-breakfasts, and other lodging accommodations. Lodging taxes levied by state and local governments share common characteristics but are known by various names, including hotel occupancy tax, hotel-motel tax, room tax, bed tax, transient occupancy tax, tourism improvement tax, and others. States authorize the imposition of lodging taxes, except in home rule cities.[5] States may tax lodging as a part of a general sales and use tax, a specific lodging tax, or both. For most lodging taxes, state legislation defines the tax base, determines who is exempt from the lodging tax, and establishes collection procedures. State, county, and local governments also impose lodging taxes, which may distribute tax revenues to their general, special revenue, or debt service funds. In many cities, state and municipal governments have formed special districts to levy additional lodging taxes on hotels within a defined geographic area. Different districts within a city may have varying rates of lodging taxes. Certain state and local governments also impose excise taxes on lodging at a fixed amount per unit of sale, such as a $1.00 per-room-night fee for furnishing a hotel room.

From a political perspective, lodging taxes may be easier to impose than other taxes because visitors who use lodging accommodations are not constituents of the local municipalities. Typically, hotel operators collect the tax from guests and receive a small administrative fee of one or two percent of collections.

While the tax's legal incidence may fall on the consumer, the economic burden of the lodging tax is shared by both lodging providers and their guests. A lodging tax raises the price of lodging accommodations. Depending on the elasticity of the supply and demand for lodging, the hotel manager may be unable to increase their room rates enough to compensate for paying the full amount of the tax. Since the elasticity of supply and demand changes depending on market conditions, the true incidence of a lodging tax varies as market conditions change. This study does not attempt to estimate the economic incidence of lodging taxes.

Hotel owners are often willing to cooperate with local governments to impose lodging taxes dedicated to tourism promotion and the construction of convention centers. For hotel owners, tourist-oriented public facilities and advertising serve as drivers of room demand. All hotels in a given market can benefit from programs that bring tourists and convention attendees to a city. Sponsoring these types of programs would be prohibitively expensive for any individual hotel. In the case of convention centers funded by a lodging tax, the hotels and individuals who benefit from the center pay for its construction and maintenance. Municipalities seek to benefit from visitor spending and the associated tax revenue generated by convention centers. By imposing lodging taxes, those who benefit pay for advertising, marketing, and sales efforts funded by lodging tax revenue.

Some states, particularly those with large tourism industries, prevent municipalities from depositing hotel tax revenue into their general funds. For example, Florida allows only a series of special-purpose taxes for tourist development. Texas requires local transient occupancy taxes to fund convention center development or tourism promotion.

Since the 1970s, lodging taxes have become commonplace across the country. Of the 150 largest U.S. cities examined in this study, more than 125 impose a dedicated tax, and all collect some form of taxation on hotel room revenue. In small suburban cities and major tourist destinations, lodging taxes have become a significant source of funding for economic development initiatives. This study aims to survey hotel tax implementation nationwide, providing information for those seeking to compare the structure and revenue capacity of lodging taxes across diverse markets.

Changes in Lodging Tax Rates

State, county, and local governments enacted several rate changes that took effect during fiscal year 2025. Recent changes in lodging taxes in cities include the following:

Recent Changes in Tax Rates

Source: Respective Jurisdictions
 
In addition to the 2025 county and local rate changes, we anticipate the following changes for the next several years.

Projected Changes

Source: Respective Jurisdictions

State Tax Rates

All but two states impose a sales tax, a lodging tax, or both on overnight transient accommodations. Municipal governments impose lodging taxes in two states (Alaska and California) that do not tax hotel lodging. Twenty-six states impose a separate lodging tax on hotel stays. In fifteen of these, the lodging tax is the only state tax on hotel rooms, while the other eleven also apply their general sales tax.

States with high lodging tax rates typically have more restrictions on imposing local lodging taxes. To illustrate, Connecticut has the highest statewide lodging tax rate at 15% but forbids all local authorities from imposing additional lodging taxes. On the other hand, Oregon imposes a low state lodging rate but does not restrict local taxes.


Source: Respective Jurisdictions

Appendix A, which can be found in the full download of the 2026 HVS Lodging Tax Report, presents a detailed description of each state’s lodging taxes and annual revenue collections.
 
State Lodging and Sales Taxes Imposed on Hotels
Source: HVS and Respective Jurisdictions
 
The following table lists the sales tax, lodging tax, and total tax rate levied on lodging accommodations. It ranks the 50 states by the total tax rate applied to lodging.
 
States Ranked by Total Ad Valorem Tax Rates on Lodging Accommodations 2025

Source: Respective Jurisdictions

State Lodging Tax Revenue

HVS analyzed annual state lodging tax revenues as reported in comprehensive annual financial reports, most of which use a modified accrual basis for revenue reporting. We recorded government estimates from budget reports in a few states where the final audited information was unavailable for fiscal year 2025. Government agencies sometimes provide annual lodging tax collection data instead of modified accrual data. Accrued revenues are recorded in the period in which the liability for tax payment occurs. Cash collections typically lag the period of liability by at least one month.

Depending on the size of their tax liabilities, taxpayers may remit payments on a monthly, quarterly, or annual basis. Administrative charges, payment of back taxes, and penalties may also affect the reported revenues, but the amounts are small. Only sales tax revenues in the accommodations sector were available in some states. Whereas lodging taxes are typically applied only to hotel room charges, sector-wide taxable sales might include other sources of taxable revenue, such as food and beverage revenue. We did not attempt to estimate the percentage of taxable sales due solely to overnight stays.

Among the states that collect lodging or sales tax on hotel rooms, total revenue increased by 2.5% in 2025 compared to 2024. This modest growth follows a 4.1% increase in 2024 and a strong 18.2% increase in 2023. The smaller increase in 2025 suggests that revenue growth is beginning to stabilize. Notably, not all states that reported lodging tax revenues in 2025 saw year-over-year increases, indicating that the strong growth of prior years has started to level off.

The following table presents a six-year history of lodging tax revenue for each of the twenty-five states that have imposed a dedicated lodging tax. Revenue reported from past years has been adjusted for inflation. Data is presented in millions of dollars, and the states are ranked by 2025 revenues.

Rank of States by 2025 Lodging Tax Revenues (millions)

Source: Respective Jurisdictions

Total Lodging Tax Rates

HVS researched the total tax rate applied to lodging accommodations in the 150 most populous US cities as projected from the 2010 census. The total tax rate comprises all state, county, city, and special district taxes levied on lodging facilities within the city's urban center, where the highest special district taxes may be applied. The following tables list the tax rate applied to overnight stays at lodging facilities at the state, county, city, and special district levels, as well as the total rate imposed on an overnight stay at a lodging facility in the urban center of each of the 150 largest cities in the United States.
 
Source: Respective Jurisdictions

To calculate the special district rate, HVS calculated the tax rate an overnight visitor would pay to stay at the hotel with the highest tax rate within a special taxing district. Due to special taxing districts, the tax rate at a particular hotel can be influenced by its location, size, or other factors that determine tax rates. The figure below shows a distribution of combined lodging tax rates in the 150 largest U.S. cities.

Frequency of Total Lodging Tax Rates
Source: HVS and Respective Jurisdictions

The following table ranks 150 cities by total lodging tax rate. If state or local general sales taxes apply to lodging sales, this rate includes the total tax rate. This analysis enables a comparison of cities’ total tax rate. The figure below provides a breakdown of tax rates by government unit.
 
Top 150 Urban Centers Total Lodging Tax Rate Ranking 2025*

Source: Respective Jurisdictions
 
Tax Rates in Top 150 Urban Centers 2025

Source: Respective Jurisdictions
 
Tax Rates in Top 150 Urban Centers 2025 - Continued

Source: Respective Jurisdictions
 
Tax Rates in Top 150 Urban Centers 2025 - Continued
Source: Respective Jurisdictions

City Lodging Tax Revenue

The following tables describe the lodging tax revenue that the 150 most populous cities collected from lodging taxes. Unless otherwise noted, the tax rate and revenue listed only pertains to the citywide lodging tax and excludes special district or city sales taxes. Unlike most lodging tax revenues, sales tax revenues typically flow to general government funds and are not separately reported for the lodging sector.

Consequently, the revenue figures presented for comparable cities can diverge greatly. For example, a city in California with an average lodging tax rate will show greater revenue year over year than a similar city in Nevada, where taxes are levied primarily at the state and special district level. For individual cities, revenues are reported from consistent sources each year.

In some states and cities, lodging taxes are imposed by the county rather than city level. For example, cities in Florida, Indiana, and parts of New York do not levy municipal lodging taxes. In such cases, we list county lodging tax revenues. Year-over-year revenue changes may reflect tax rate changes and underlying changes in taxable receipts for lodging.
 
Reported Lodging Tax Revenues in Top 150 Urban Centers ($ Millions)

Source: Respective Jurisdictions
 
Reported Lodging Tax Revenues in Top 150 Urban Centers ($ Millions) - Continued

Source: Respective Jurisdictions
 
Reported Lodging Tax Revenues in Top 150 Urban Centers ($ Millions) - Continued
Source: Respective Jurisdictions

Excise Taxes

In addition to percentage taxes on gross room revenues, some hotels are subject to excise taxes on lodging transactions and may be charged a flat fee per room night. Excise taxes tend to be less volatile because they only depend on occupancy and are not subject to room price variations. However, excise taxes do not grow with inflation or room rate increases.

Hotels in 23 cities are subject to a state, city-wide, or special district excise tax. Excise taxes range from $0.75 to $5.00 per room night, with an average of $2.80. HVS calculated each city’s excise tax as a percentage of its per diem rate (in fiscal year 2025 dollars) to estimate effective tax rates. A city’s effective rate indicates the average rate a person pays if the excise tax were included as a percentage of the total sale price. For this example, HVS used the per diem rates set by the General Services Administration (GSA). The per diem rates set by the GSA are usually lower than the average daily rates at hotels in the specified areas. The chart below is for illustrative purposes only.

On average, every dollar charged in excise tax is roughly equivalent to an ad valorem tax increase of 2.03% for 2025.

Selected Effective Rates of Excise Taxes

Source: HVS, GSA, and Respective Jurisdictions

Airbnb Lodging Tax Collections

Short-term home rental services such as Airbnb and VRBO have grown even more popular among travelers, with Airbnb being the dominant player in the market. 2025 marked another record year for Airbnb, with total revenue of $12.2 billion, a 10% increase from 2024, which had previously set a record. Growth was driven in part by an 8% increase in nights and experiences booked, which reached 533 million. Listings in North America accounted for 42% of 2025's revenue, down from 45% in 2024, as growth in Europe and Latin America outpaced North America. Often referred to as part of the sharing economy, these peer-to-peer platforms enable homeowners or hosts to rent out a spare room, an entire house, or an apartment to travelers seeking unique travel experiences and accommodations. Airbnb has experienced exponential growth since its founding. In 2025, Airbnb's adjusted EBITDA reached $4.3 billion, up from $4.0 billion in 2024, reflecting continued strong business performance.

In response to Airbnb's growth, cities have been compelled to address challenges stemming from the impact of short-term rentals. Residents have raised concerns over the neighborhood impacts of transient visitation. In response, many cities and states have imposed new taxes and regulations on short-term rentals.

To gain legitimacy and permanence within the United States, Airbnb has urged local governments to permit it to collect and remit lodging taxes on behalf of its hosts. In recent years, states and cities have made considerable efforts to collect taxes from Airbnb. Since January 1, 2025, Delaware has imposed a 4.5% short-term rental lodging tax on all short-term rentals, including those listed on platforms such as Airbnb. Hawaii remains the only U.S. state in which Airbnb does not collect and remit taxes on behalf of the state.

Click here to download the full 2026 HVS Lodging Tax Report.

Disclaimer

HVS’s lodging tax study recognizes that lodging tax rates, collections, and distributions are in constant flux. The data presented herein are HVS’s best attempt to gather the most recently available information. HVS used sources deemed to be reliable and assumes that this information is accurate. All questions, comments, or concerns are welcome in the continuing process to accurately present the current and historical trends of lodging taxes in the United States. 

[1] HVS, "How the 2026 FIFA World Cup Changed US Hotel Markets," Retrieved August 6, 2026.

[2] US Congressional Research Service, "Supreme Court Rules Against Tariffs Imposed Under the International Emergency Economic Powers Act (IEEPA)” Congressional Research Service," Retrieved October 8, 2026.

[3] Oxford Economics, "Oxford Economics," Retrieved October 8, 2026.

[4] Typically defined in ordinances as being fewer than thirty days.

[5] Home rule cities are cities that have their own taxing authority, have adopted home rule charter for their self-governance, and are not limited to exercising only those powers that the state expressly grants to them.